A new report from the Thomson Reuters Institute and Tax Executives Institute offers a vision for the corporate tax department of 2030, and poses four key questions tax leaders need to be asking now.
Executive Summary
The future is arriving quickly for corporate tax departments, whether they’re ready for it or not. The acceleration of technology development — especially AI — along with evolving needs for resources and skilled talent, as well as specific expectations from their organizations’ C-Suites are swiftly and dramatically changing the landscape for tax departments.
More critically, clear differences are emerging between departments that are excelling in these areas and those that are struggling to keep up with the rapidly changing tides.
Amid these swirling currents, tax department leaders have a clear vision for where they want to steer their function. Indeed, process automation and AI integration are now the top priorities for tax departments, survey respondents say, edging out past top concerns such as compliance and audits. And when we asked them to define the course that they intend to follow into the future, leaders responded that they both understand and are clearly contemplating the direction in which they want to go.
The operating model that tax departments need to embrace for the future involves one that considers all facets of the department, from planning, workflows, and talent to resourcing and technology.
However, there are some areas in which many tax leaders are faltering. Roughly half of survey respondents say they consider their tax department only somewhat or not very successful, struggling with automation, resourcing, and visibility. And there are concerns about how the department is seen by senior management — almost three-quarters of respondents feel their departments are primarily viewed as cost centers.
Moving toward a fundamentally different operating model
The operating model that tax departments need to embrace for the future involves one that considers all facets of the department, from planning, workflows, and talent to resourcing and technology. Department leaders are aiming to make their teams more efficient, more timely and accurate in their work, and more strategic and visible in their contributions to the organization.
However, progress towards reaching those goals is uneven. While some departments are making strong initial strides, others have the same goals but are unclear about the right path for achieving them. In this year’s iteration of our State of the Corporate Tax Department identifies clear distinctions between the two groups, as well as actions the latter group can take to close the gaps.
Any discussion about future direction inevitably involves technology, and specifically, AI. While definitely central to the technology conversation and most certainly on the minds of tax department leaders, AI is far from the leading story according to many of the corporate tax professionals we surveyed. Indeed, the path forward is complicated, and it’s more grounded in the fundamentals of the function and operation of the tax department — as well as its positioning in the organization — rather than any single silver bullet of technology.
Tax leaders say they know what they want their tax departments to become, and in some cases — but not all — they also say they know how best to get there. This year’s report breaks down those needs, plans, expectations, barriers, and solutions — along with the fundamental considerations that tax departments must navigate each day to reach their desired goals.
As the report illustrates, corporate tax leaders need to start by answering four foundational questions that will give their department and its tax professionals the best path forward, one in which their success becomes as achievable and clear as their goals.
Key takeaways
- Tax departments are evolving towards a more strategic model — Tax leaders foresee that by 2030, their departments will be more integrated with the business as a strategic partner, not merely a compliance function.
- Despite the clear vision on where they want to take their departments, progress is often slow — Most tax departments are still only in the planning or early stages of achieving their vision.
- Tax leaders are split on current success — Roughly half of respondents say they consider their department to be successful or exceptionally successful. And that means that half do not as they struggle with issues such as automation, resourcing, and visibility within the organization.
- Being seen as a cost center is still prevalent —Almost three-quarters (73%) of respondents say their tax departments are primarily viewed as cost centers. Those that feel their departments are seen as value creators are eight times more likely to consider their department exceptionally successful.
- Under resourcing remains a persistent problem — For the third consecutive year, more than half of respondents say their departments are under resourced, forcing them to turn to creative solutions other than increasing budgets and headcount.
Success, achievements & the tax department of the future
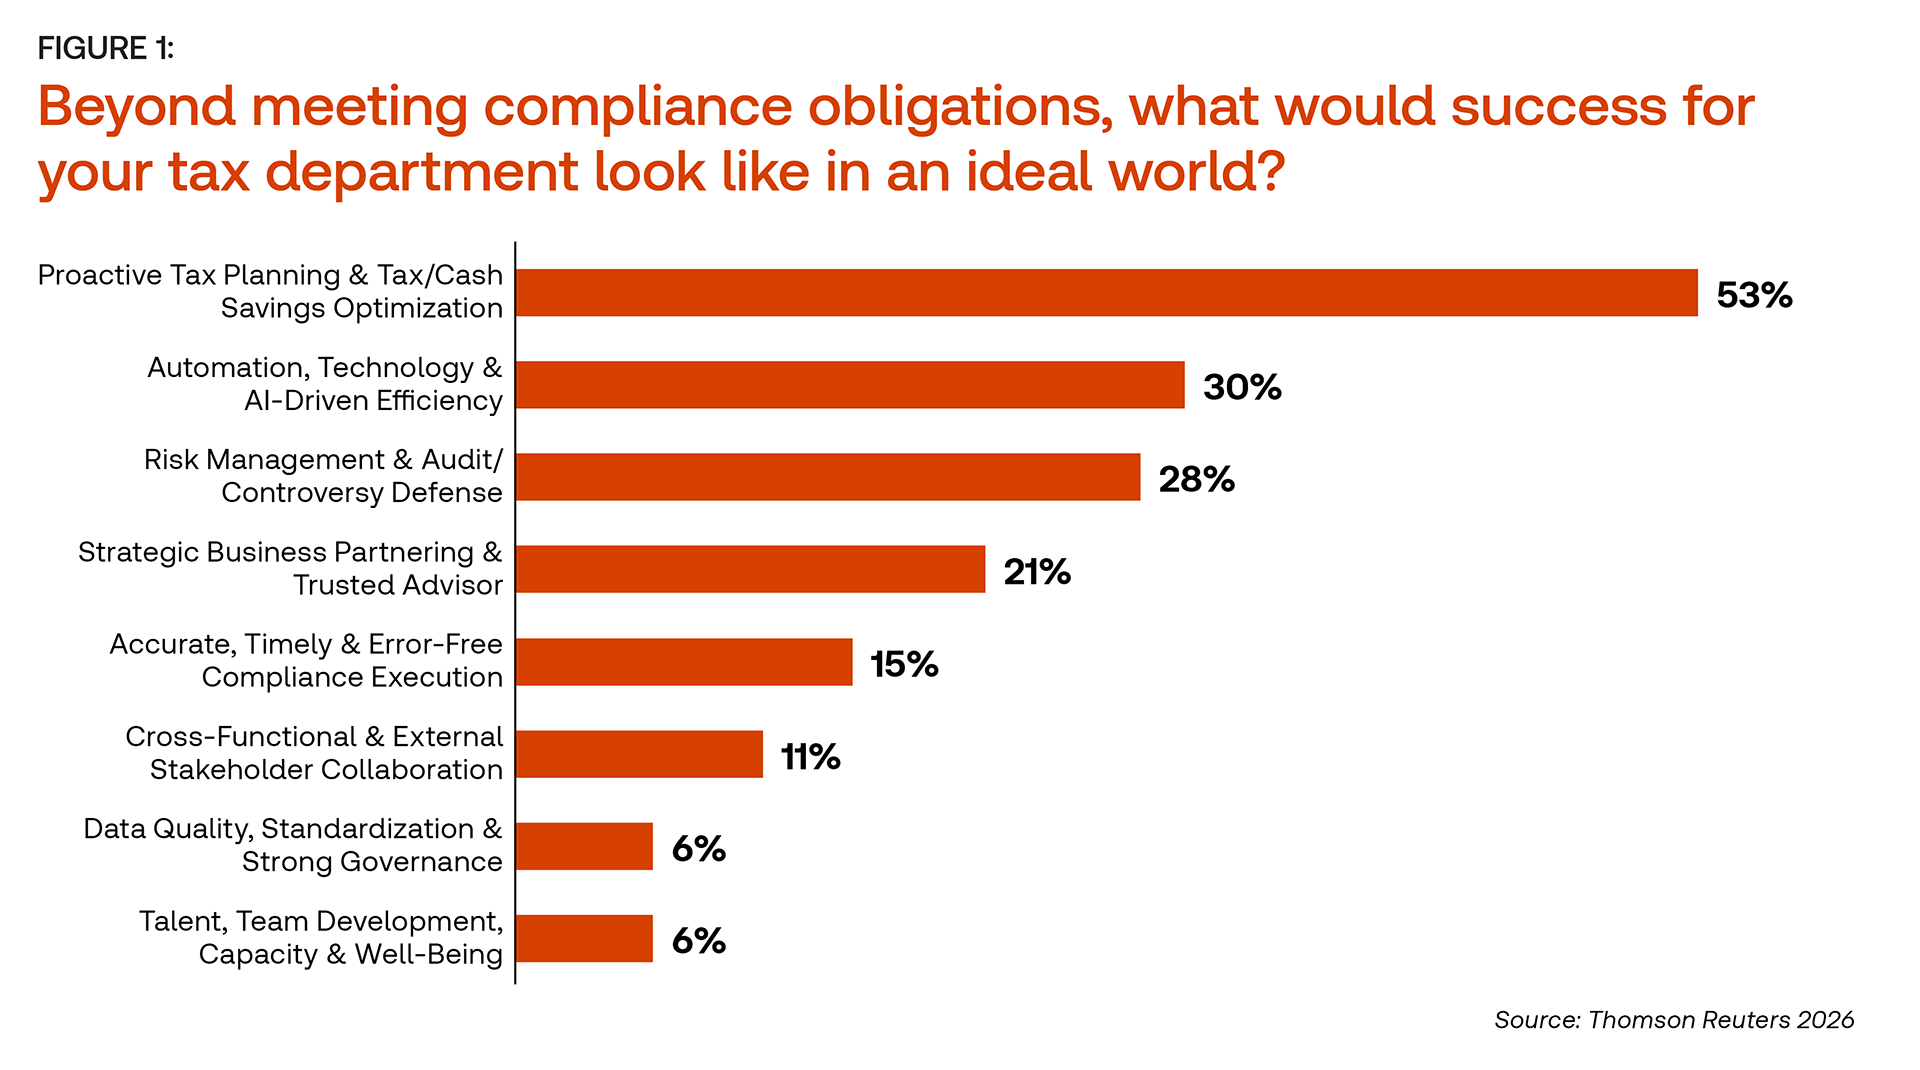
We asked tax leaders, beyond meeting compliance obligations, what would success for their corporate tax department look like in an ideal world?
More than half described a department that provides proactive tax planning, and optimization of tax and cash savings.
That means respondents are clearly envisioning their departments evolving into a more proactive, strategic partner to their organizations.
The responses describe a tax function that stops treating timely and accurate filings as a ceiling. In fact, one respondent explains that they want their department to “be viewed as a profit center and business partner by the business units and senior leadership.”
“In an ideal world, success for the tax department [is] measured by being a source of speed and value in the business.” — Corporate tax leader
Another describes both the ambition and the challenge: “In an ideal world, success for the tax department isn’t measured by filings, it’s measured by tax being a source of speed and value in the business. However, the first and key step to this would be to have all the returns automatized and the data fully aligned, which is a clear challenge for the tax team.”
Defining success & giving mixed grades
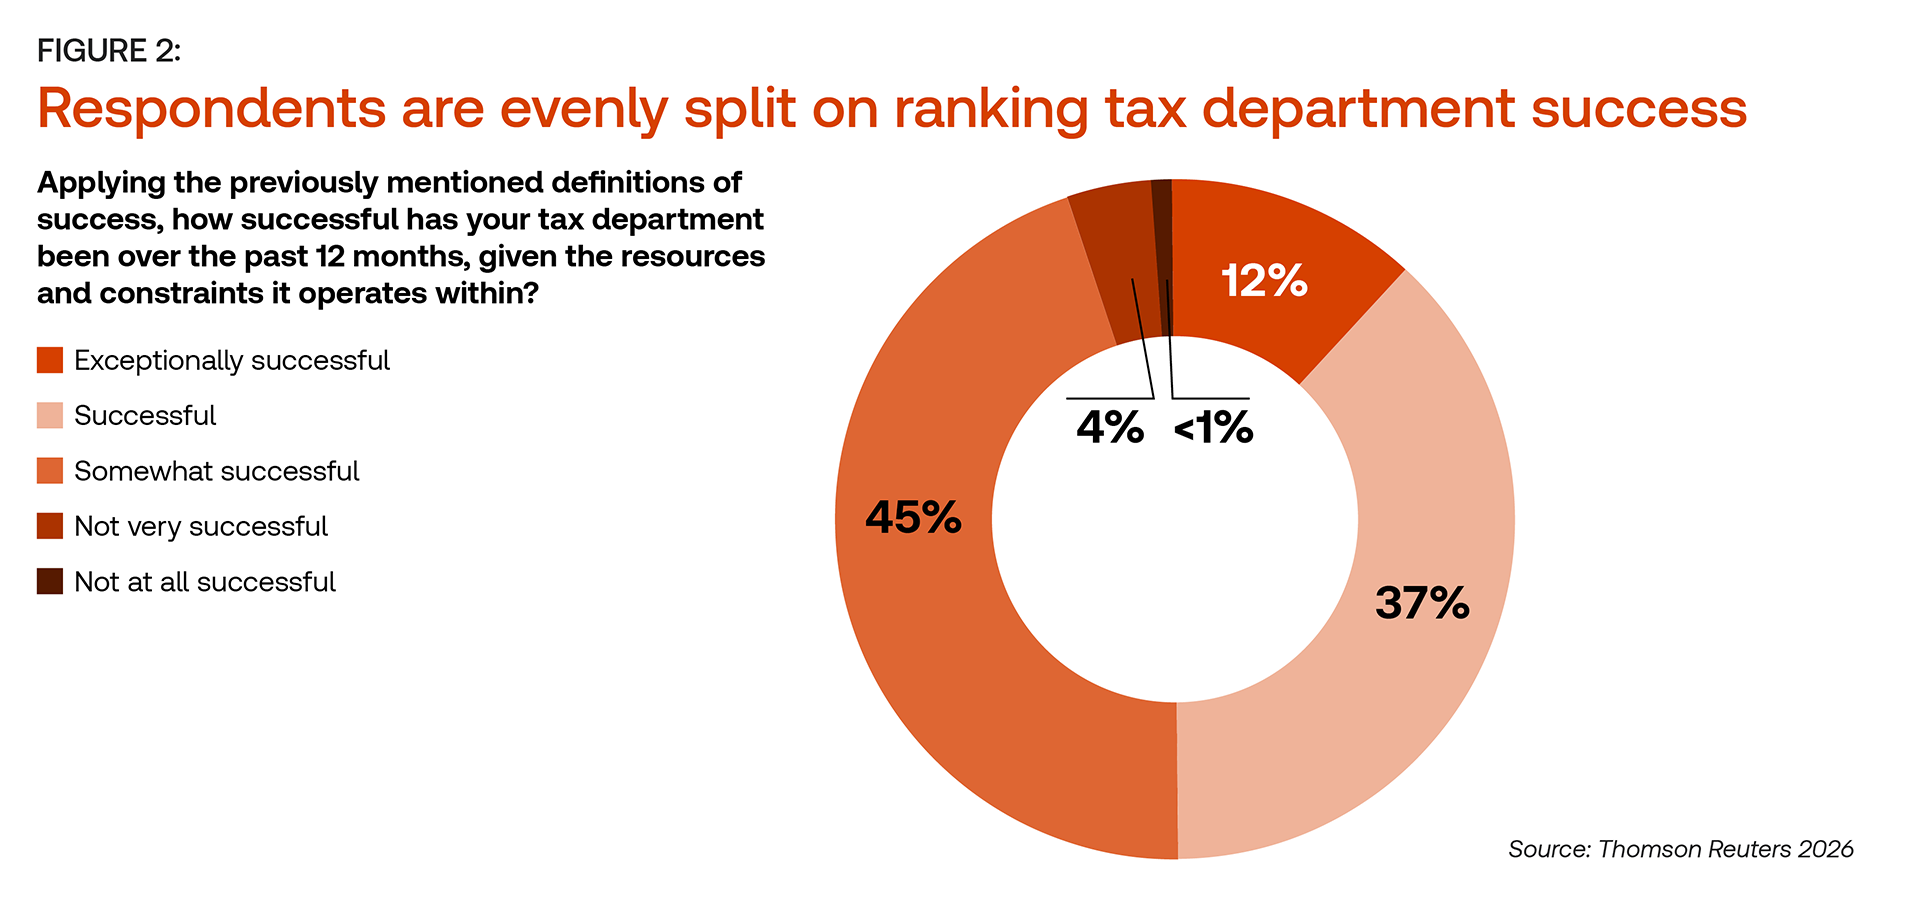
However, when turning the view from the ideal tax department of the future to the daily workflows of today, the picture becomes mixed and respondents are evenly split. About half consider their department to be exceptionally successful or successful, while the other half rank their department as just somewhat or not very successful.
What they’re proud of & what they’re missing
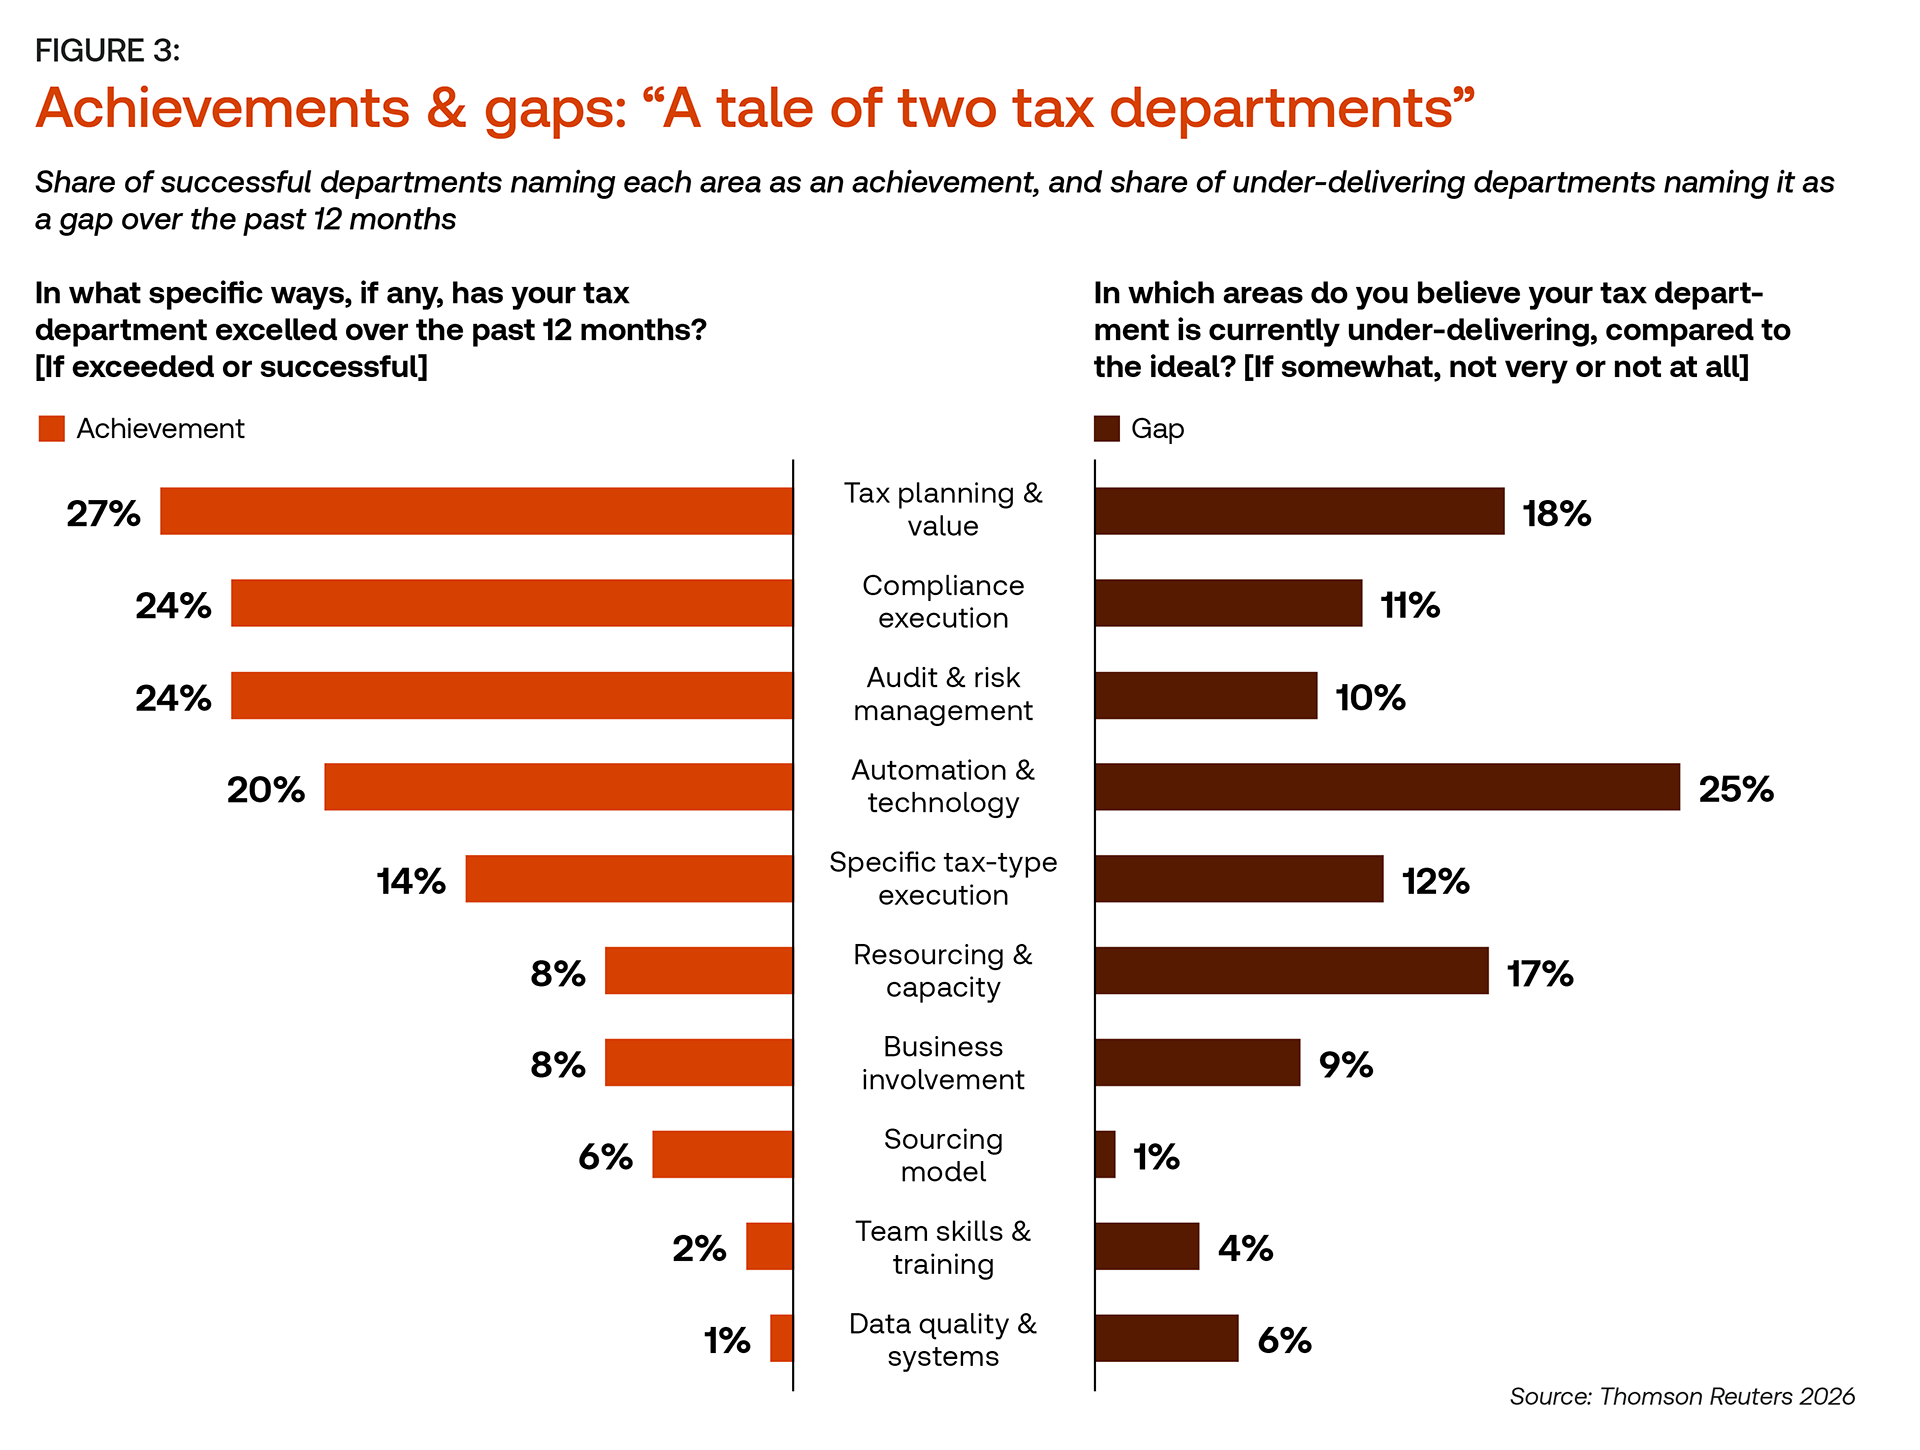
When we asked those respondents who say their departments are successful or exceptionally successful in which areas they are excelling, they rate themselves highly for tax planning and value, compliance execution, and audit & risk management. Then, we asked those respondents who say their departments are only somewhat successful or not very successful in which areas they are underdelivering, they say they’re struggling with automation & technology and resourcing & capacity.
Interestingly, these answers show that the difference between the two groups is not about execution, it’s about infrastructure. Less successful departments lack sufficient resources — whether skilled personnel or advanced AI-driven tools — to provide adequate capacity for work. Unfortunately for these department, this lack of resources begins a downward cycle that also reduces their ability to achieve their goals of providing more proactive and strategic contributions to the organization.
4 key questions tax department leaders need to be asking now
Success is about more than resources, capacity, and automation, of course. These factors are essential, but they are largely the structural components for producing output.
Those respondents who consider their departments to be successful or exceptionally successful also identify specific attributes more so than those that see their departments as less successful. The key separating elements can be identified with four questions that tax leaders need to ask themselves in evaluating their department.
Question 1: Is our tax department viewed as a value creator?
Identifying how the tax department is viewed within the organization is critical for understanding a successful department. It’s a function of both the work that the department is conducting and how effectively the value of that work is being communicated.
More than one-quarter of respondents (27%) say they believe their department is considered a value creator, or at least more of a value creator than a cost center.
That means, however, that almost three-quarters of respondents (73%) say their department is still seen as either a cost center, or at best, equal parts cost center and value creator.
Tax leaders who believe their departments are seen primarily as value creators are eight-times more likely to consider their department as being exceptionally successful.
The difference is strongly associated with whether a department considers itself successful or not successful. Only about 5% of respondents who say their function is seen as mostly or primarily a cost center also consider their department to be exceptionally successful. By comparison, tax leaders who say they believe their department is primarily seen as a value creator are eight-times more likely to feel that their department is exceptionally successful.
This is one of the starkest differences identified in this year’s report, and it spotlights one of the most important attributes that defines successful corporate tax departments.
Conducting quality, accurate, timely, even strategically valued work can be mere table stakes, because measuring, reporting, and communicating the value of that work to the organization plays an equal, if not greater role.
Effective measurement & communications with the C-Suite
One tax leader described the struggle to be seen as a value creator in the clearest terms: “[We are] often brought into business decisions too late to meaningfully influence outcomes… so the function is seen more as a cost center than a value driver.”
However, the roots of this perception begin taking hold much earlier in the process — and it’s driven by how the tax department’s contributions are being measured and communicated.
Respondents express near-universal confidence in their ability to articulate to senior leadership about the strategic value the tax department delivers. An overwhelming 83% say they are either very confident or at least somewhat confident in doing so.
Behind that confidence, however, there is often a disconnect in how that information is received up the chain and particularly in the C-Suite. Corporate tax departments, by and large, are succeeding in providing CFOs with metrics that go beyond compliance and that more directly measure of impact of the tax function on the organization. These metrics include tax savings, tax credits, effective tax rates, and support for M&A and restructuring initiatives.

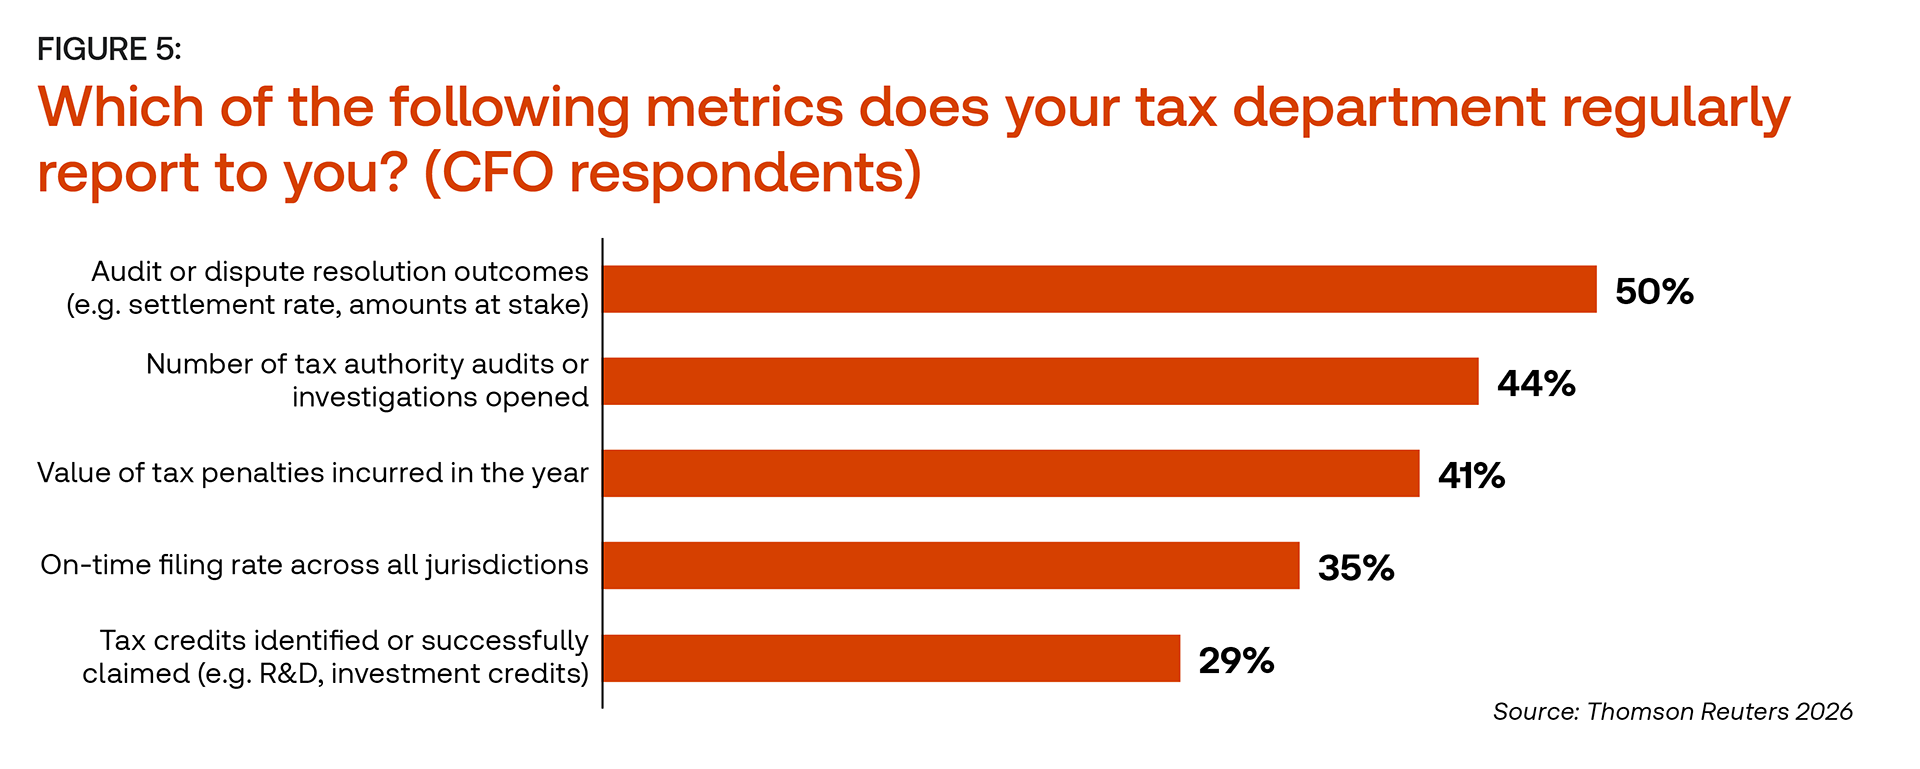
However, that does not necessarily match the view from the CFO’s desk. We surveyed a number of CFOs and the feedback is not encouraging. Several CFOs reported that, from their perspective, they are primarily receiving reports on audits, tax penalties, and on-time filing rates from their tax departments.
In other words, regardless of what’s being reported, CFOs are mostly paying attention to measures about avoiding costs. Indeed, many tax departments may believe they are sending a value narrative, but their CFOs are only seeing a risk avoidance report.
The difference may be a matter of perspective. But if all that lands with the CFO are audits, penalties and filing rates, it can become all too easy for the tax department to be seen as function that primarily manages downside, the very meaning of a cost center.
Value creators measure differently, not more
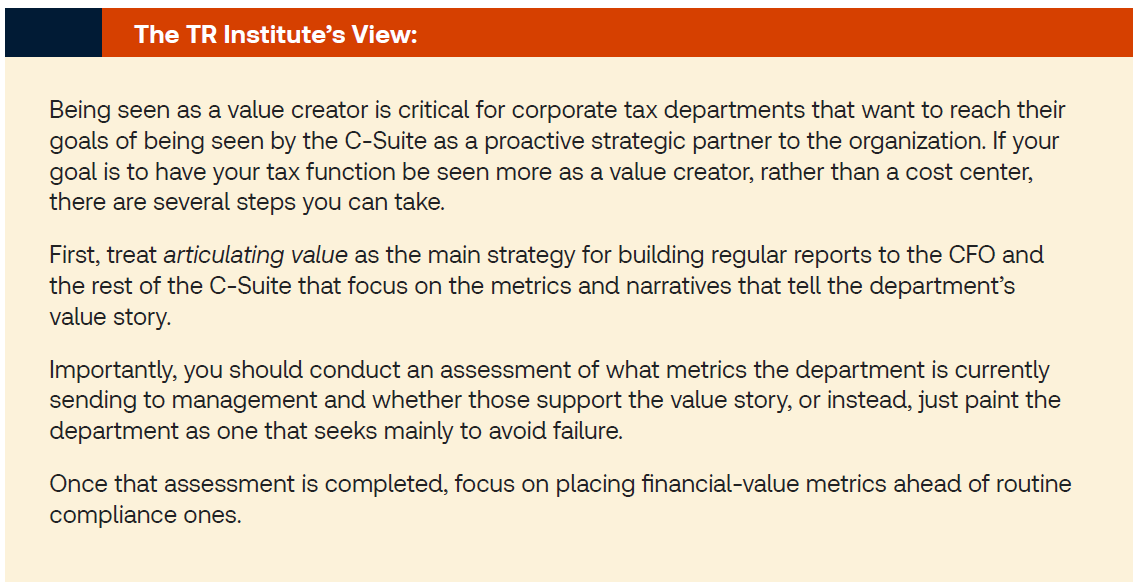
There are significant differences in the metrics reported between tax departments that are viewed as value creators and those seen as cost centers — and it’s not necessarily that value creators measure or report more metrics. Rather, it’s that those departments seen as value creators are supplying the numbers that prove financial contribution rather than those, like audit metrics, that demonstrate absence of failure.
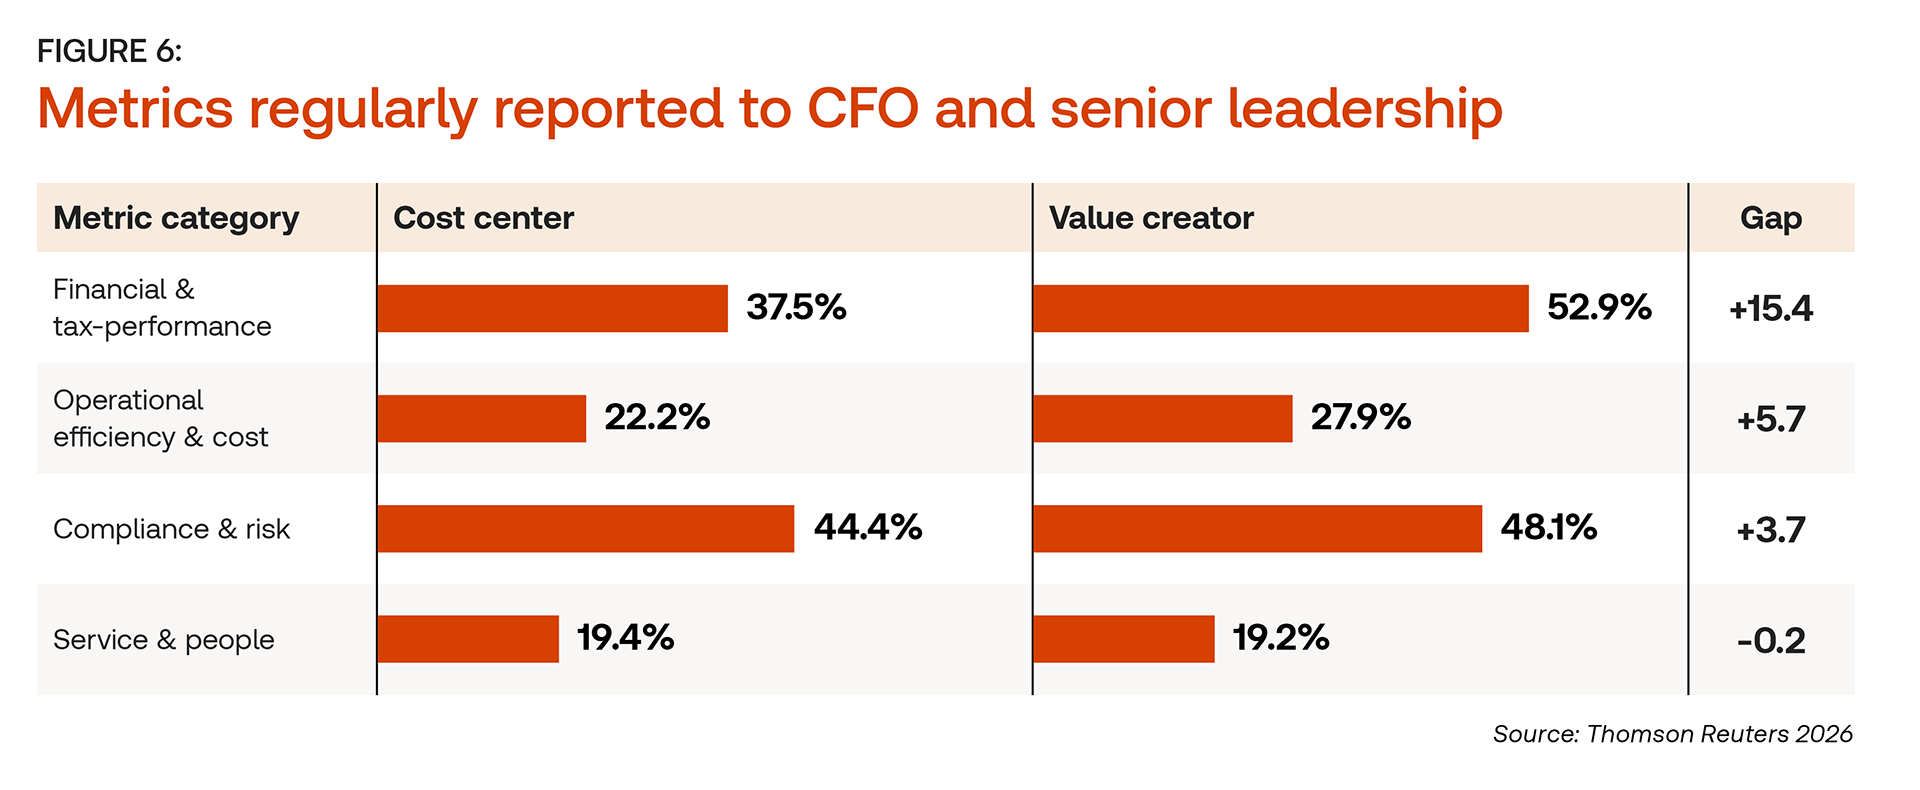
The correlation does not necessarily mean causation, of course. It’s entirely possible that organizations which understand the tax function’s contributions are already actively asking for and reviewing business impact metrics. What’s clear, however, is that business value metrics and value creators travel together and that by reporting and emphasizing specific, narrow sets of value metrics that prove financial contribution, tax departments can better their chances of being seen as a value creator.
Question 2: Is our tax department adequately resourced?
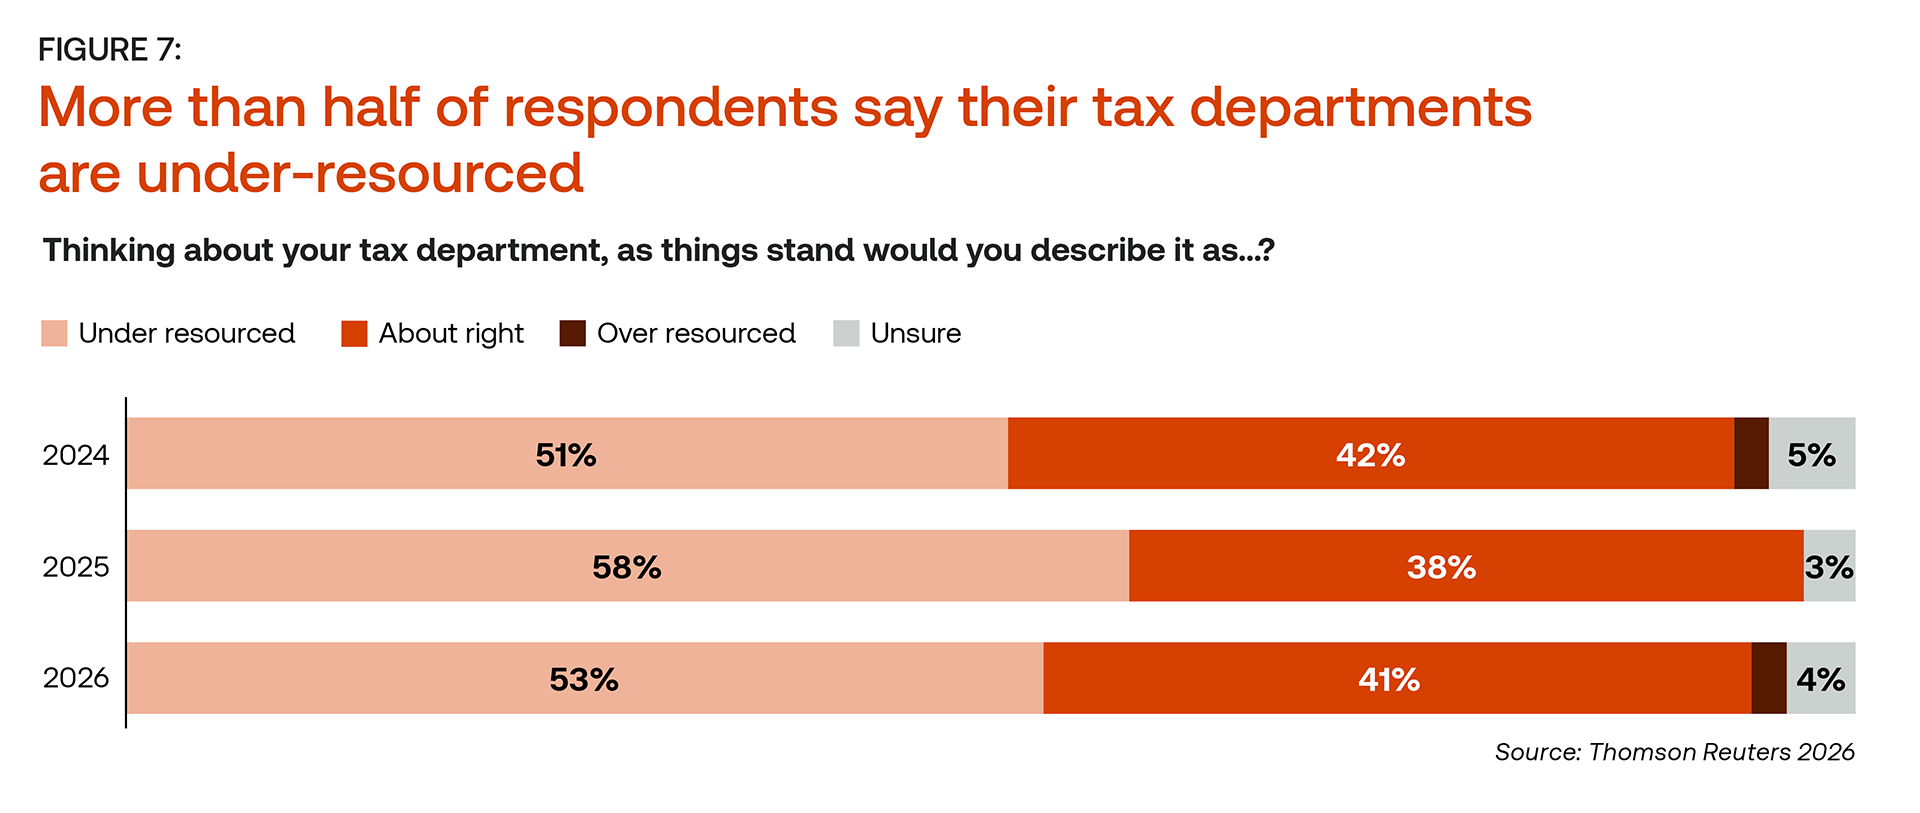
For each of the past three iterations of this report, more than half of respondents have said their tax department is under-resourced. Although the numbers improved slightly this year, they are still stubbornly consistent with the trend of recent years, suggesting that this is a structural, not cyclical, problem for many tax departments.
This is not merely a standalone issue impacting current work capacity; indeed, it also affects the department’s ability to reach its goals for 2030 and beyond.
Why departments are under-resourced
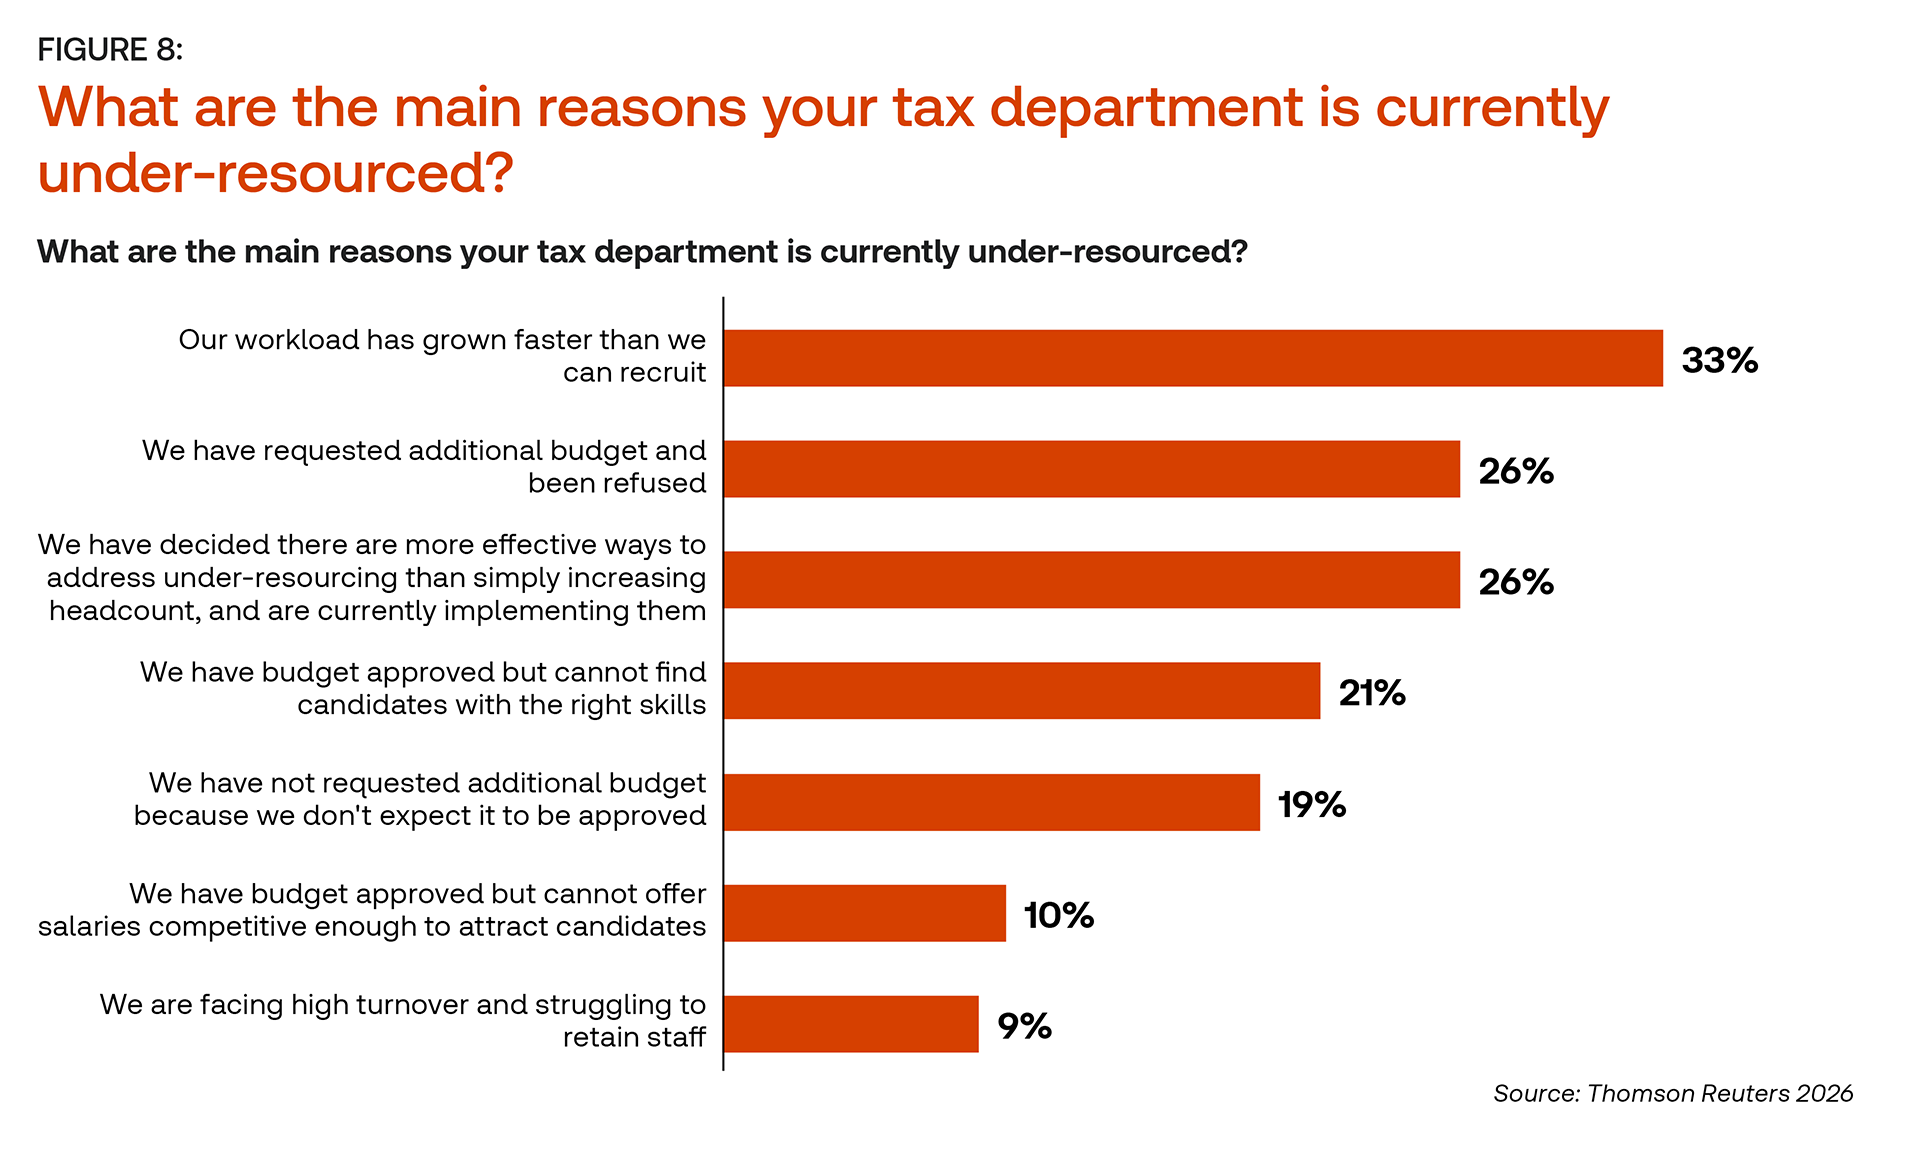
When asked to identify the main reason for being under-resourced, the most common response was that workload has grown faster than the department’s ability to recruit new talent to handle it. Budget issues are also a common chokepoint with denial of budget increases being so prevalent that one-in-five respondents from under-resourced departments say they did not even bother requesting a larger budget because they did not expect it to be approved.
Hiring difficulties also play a role. Many respondents said that even when additional budget is approved, the department often cannot find the right candidates, offer competitive salaries, or keep up with high turnover.
Strategies for addressing under-resourcing
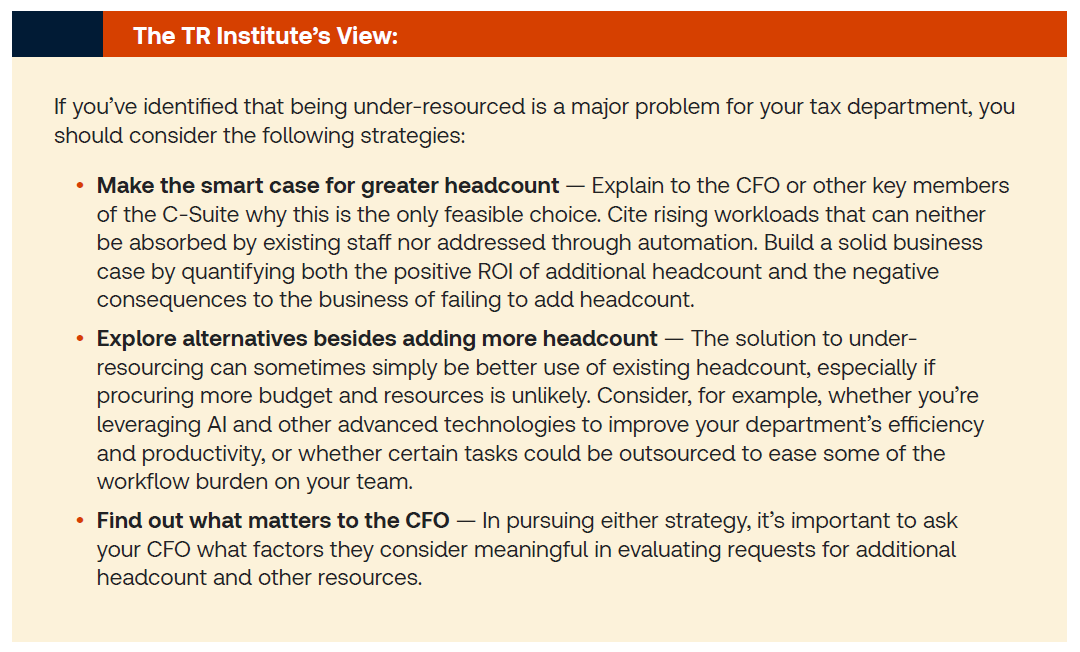
Fortunately for those under-resourced departments, these difficulties have also stimulated creative solutions. More than one-quarter of respondents have concluded there are more effective ways to address under-resourcing than increasing headcount.
Alternative approaches include process and workflow improvements, training and upskilling of existing staff, restructuring roles, and more use of shared services and centers of excellence within the organization. Many of these measures can be implemented quickly, and without needing significant additional budget.
By whatever means, maintaining or achieving adequate resourcing is one of the most common traits among tax leaders who consider their department to be successful, making them three-times more likely to view their department as being exceptionally successful than under-resourced departments.
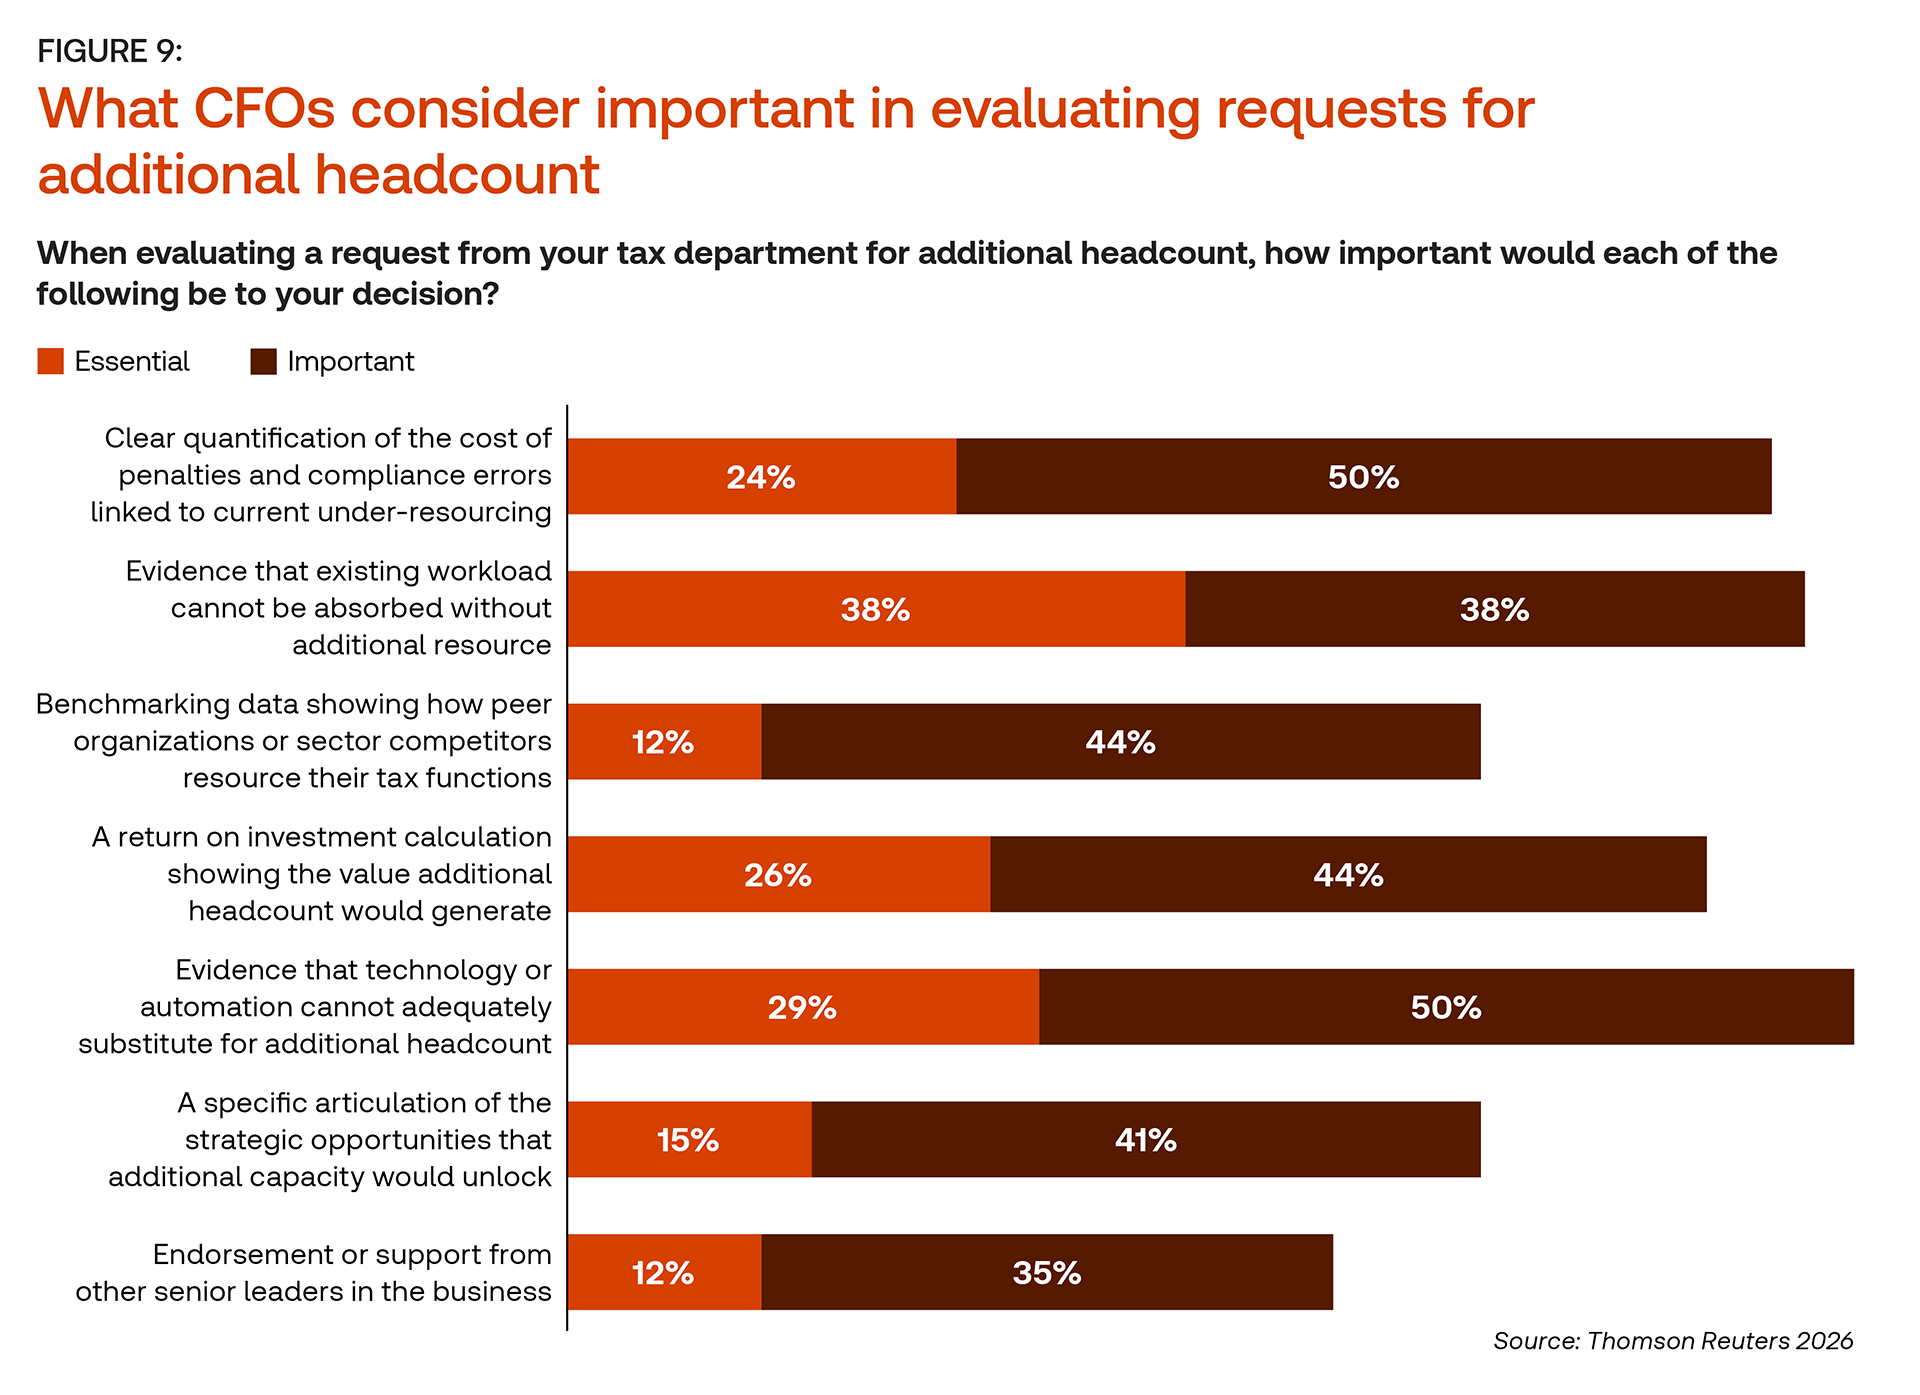
Interestingly, when it comes to obtaining more resources for the tax function, the CFOs whom we surveyed emphasized that evidence, not aspiration, is key in their evaluation. The C-Suite needs to be convinced that existing workloads cannot be handled without additional headcount or automation, and they want to see an return on investment (ROI) in the form of added value, as well as anticipated reductions in penalties and compliance errors.
Several CFOs say the factors they consider when evaluating whether to grant more resources include the new strategic opportunities that additional resources would enable, benchmarking of peer or competitor organizations, or support from other senior leaders in the organization. However, individual tax leaders should exercise their own judgment on whether those factors are meaningful to their C-Suite or not.
Question 3: How focused & effective is our technology strategy?
Increased use of automation technologies, including AI, is one of the top strategic priorities for tax department leaders — and for good reason. Among the 38% reporting moderate or significant progress, fully 91% of them say that automation and AI tools applied to-date are already saving time for their team. And more than half of the same group (58%) say it has reduced errors.
Automation and AI can also be a key driver in transforming tax departments from being seen as a cost center to becoming a value creator. Reduced time spent on manual, repetitive tasks can free up significant capacity for tackling strategic initiatives that can provide tangible value for the organization.
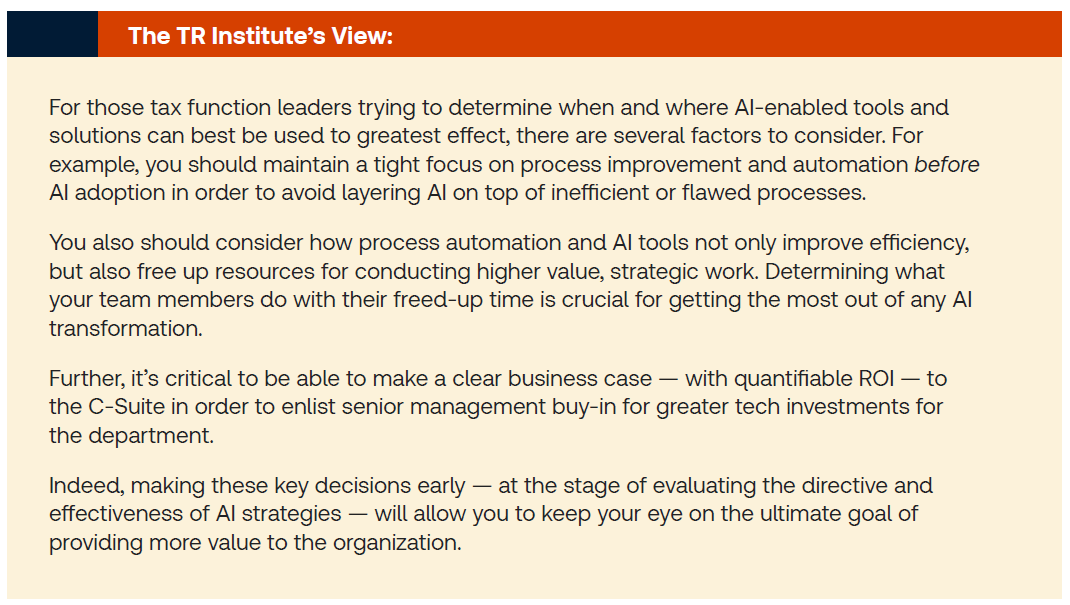
Process automation first, then AI
By far the highest priority is process automation, with more than half of respondents calling it their top technology priority. About one-third say that either generative AI (GenAI), AI analytics, or agentic AI are the most urgent need.
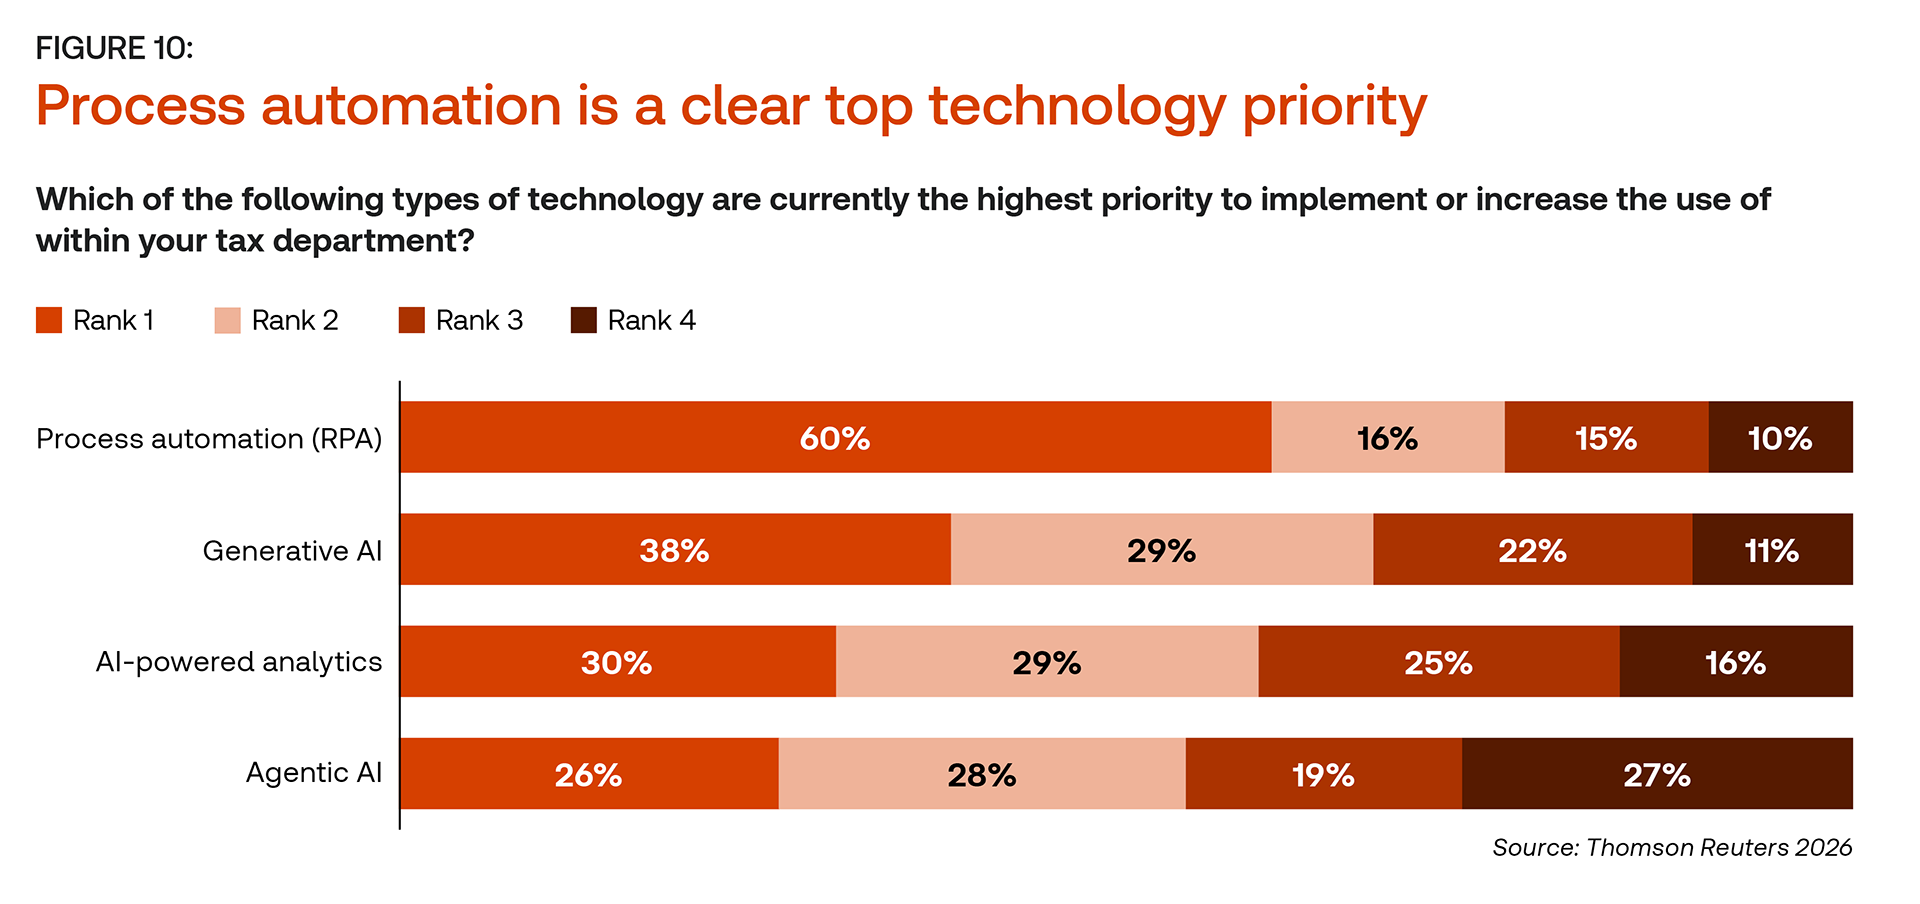
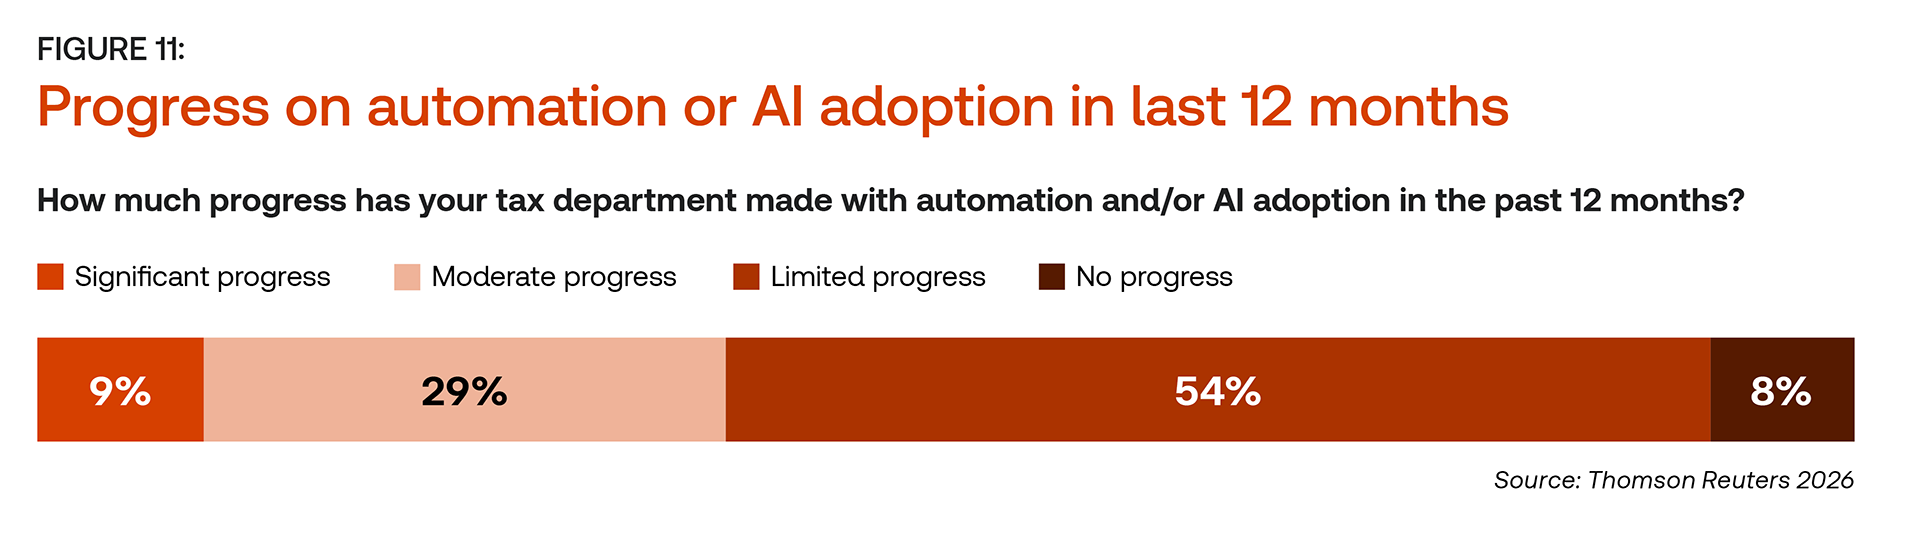
Even though these process automation and AI tools are priorities, progress has been slow. Most tax leaders (62%) note that their department has made only limited or no progress towards adopting those technologies over the last 12 months.
All of this presents both a significant opportunity and challenge for tax departments. Achieving these tech priorities could be enormously helpful in addressing lack of headcount, as well as in reaching the larger goals of greater value creation and strategic contributions to the organization.
Although 91% of respondents who have made significant or moderate progress say automation is helping their department save time, most departments have made limited or no progress on automation or AI adoption in the last 12 months.
Looking ahead at automation and AI
Naturally, respondents overwhelmingly see automation transforming the speed and the manual effort required to complete tasks. Meanwhile, AI and GenAI also are seen as transforming those activities that involve professionals’ reasoning and judgment.
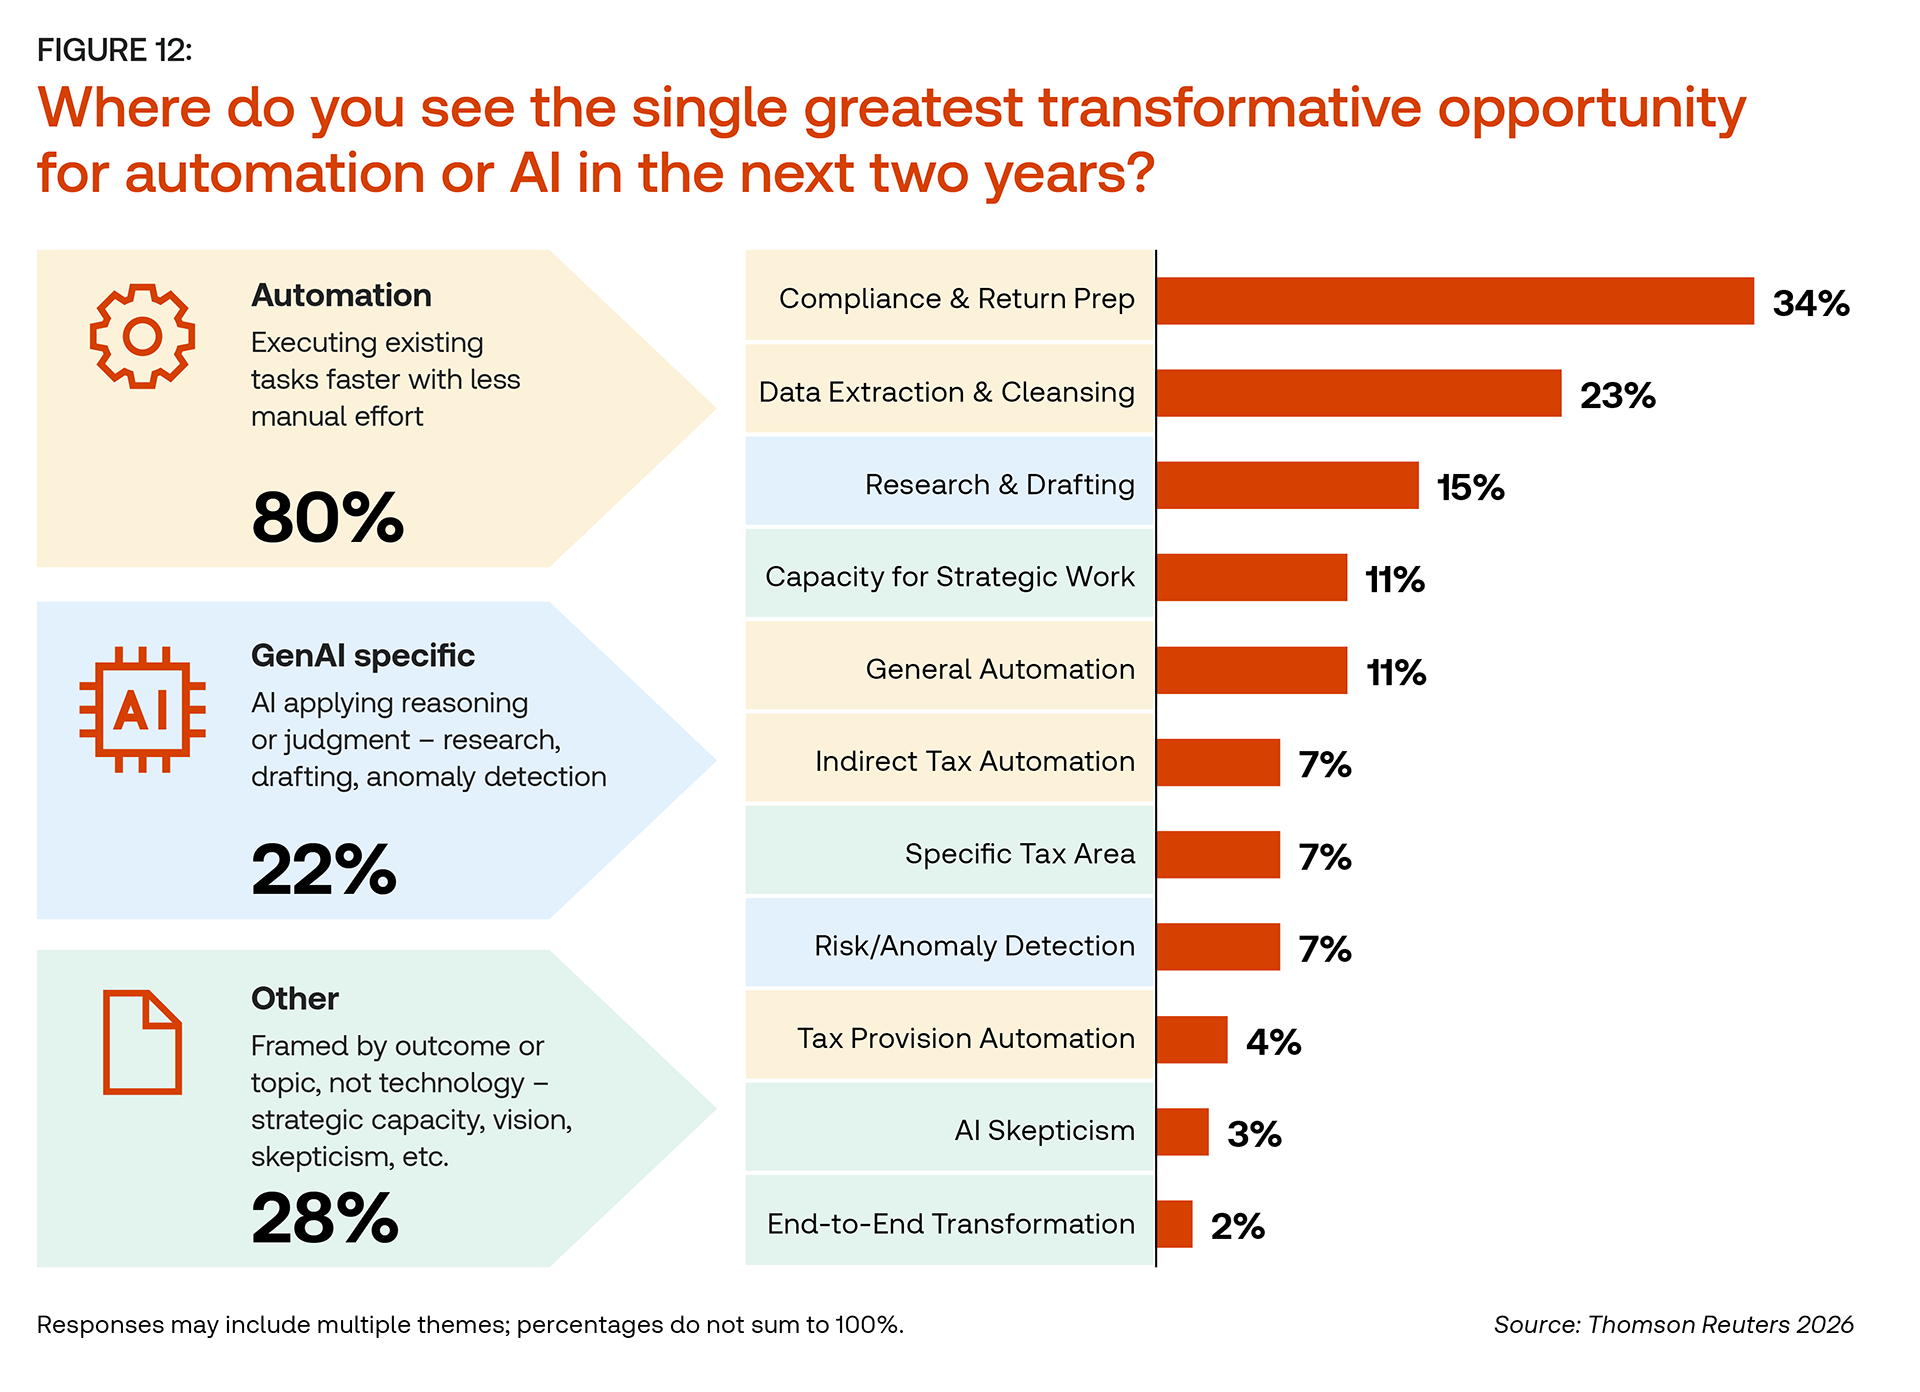
All of these AI-driven opportunities, if taken, can better enhance a tax department’s abilities to provide more strategic value to the organization while fulfilling its own compliance responsibilities with greater efficiency.
AI and the need for boundaries
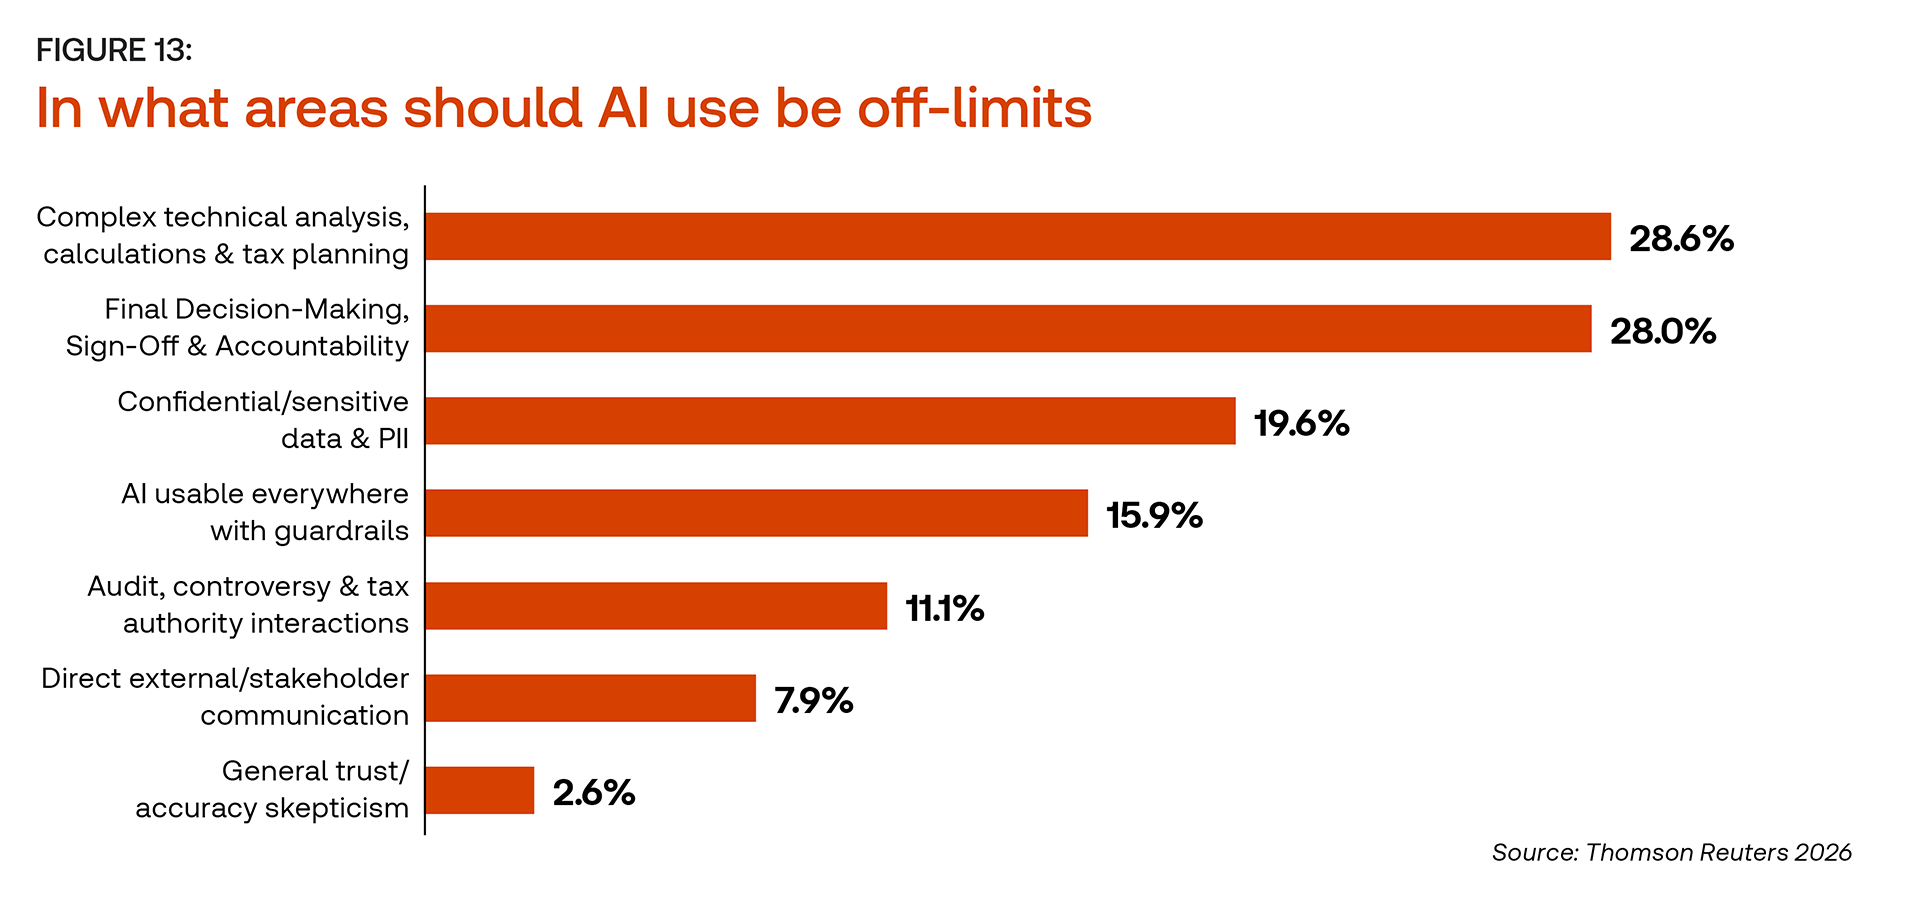
While AI may be transformative for many workflows, tax leaders are also stressing the need for clear boundaries on how and where AI is used. Fully 84% of respondents say that AI usage should be off-limits for some areas, even if controls and restrictions are in place. In particular, respondents cite the need for professional accountability, and many draw a strict line that all final decision-making, sign-off and accountability need to clearly remain in the hands of human-in-the-loop policies.
However, this opinion is not unanimous across tax leaders — one-in-six respondents believe there should be no limits on which workflows can incorporate AI so long as proper guardrails are in place.
Question 4: What is our vision for 2030?
While addressing issues of resourcing, technology, and whether the department is seen as a value creator can all help a tax department in the immediate timeframe, they also set the table for where the tax department will be in the years ahead. Most importantly, will the department be prepared for business, regulatory, and technology environments that will likely be significantly different from the ones it is dealing with today?
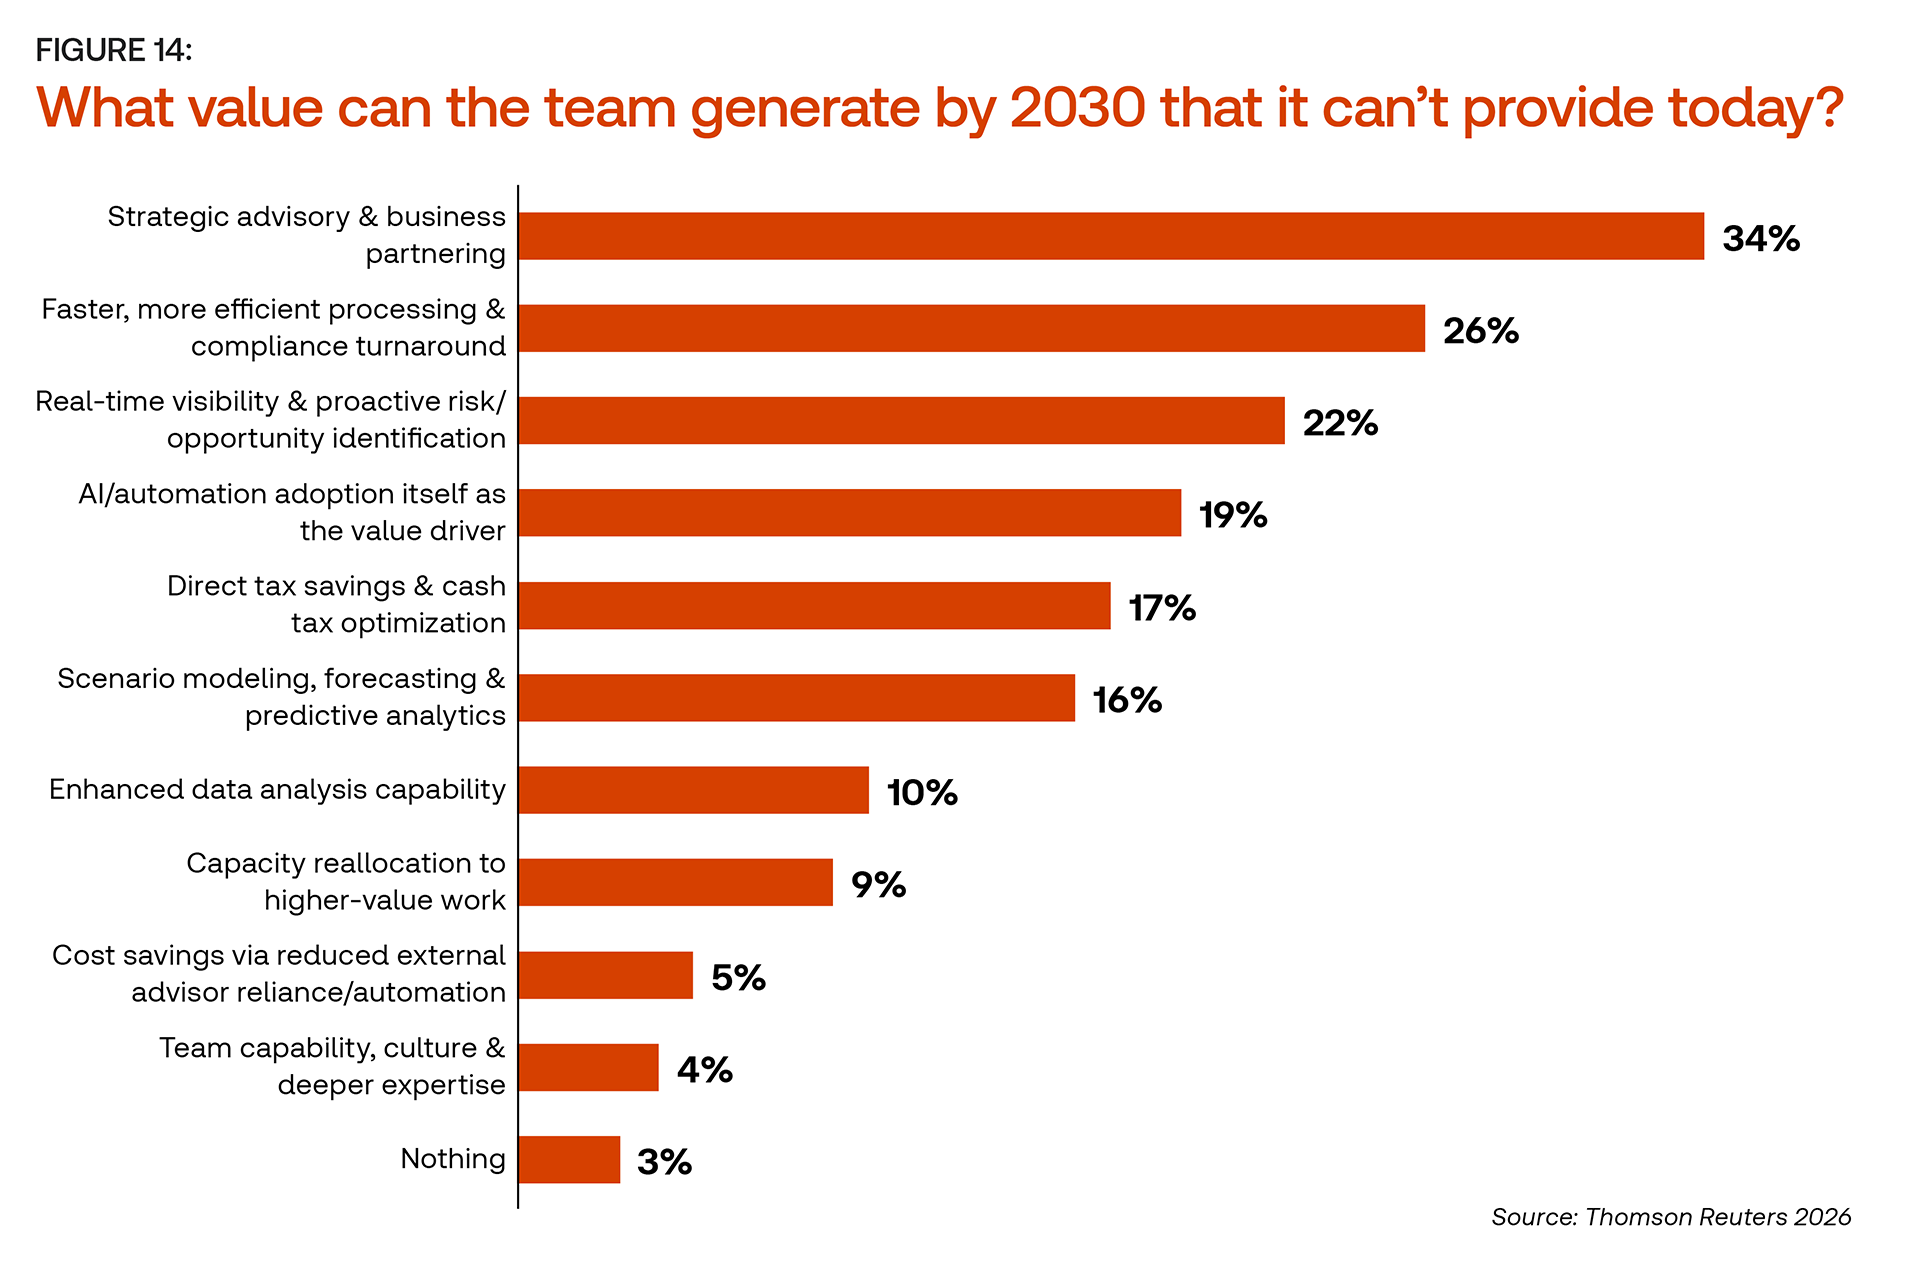
We asked the tax leaders we surveyed to imagine their department in the year 2030 and describe the ideal. Respondents expressed a goal – with unusual consistency – of a very specific operating model.
Many ways to create value
First and foremost, tax leaders foresee their department conducting more strategic advising and business partnering within the organization. Respondents used phrases such as “adding value” and “able to manage a wider workload” to describe how they see their department’s capabilities evolving.
Real-time visibility, proactive risk or opportunity identification, direct tax savings and cash-tax optimization, and scenario modeling, forecasting, and predictive analytics represent meaningful contributions to the business. In addition, these are exactly the kinds of contributions that are likely to warm a CFO’s heart.
How near is the 2030 vision?
While tax leaders have a clear vision of where they want to take their tax function by 2030, the reality today is that reaching those goals will be a major challenge for many tax departments. While more than 90% of respondents say they have started the process, only about one-quarter say they have made meaningful progress. And less than 2% have already achieved their vision or are close to doing so.
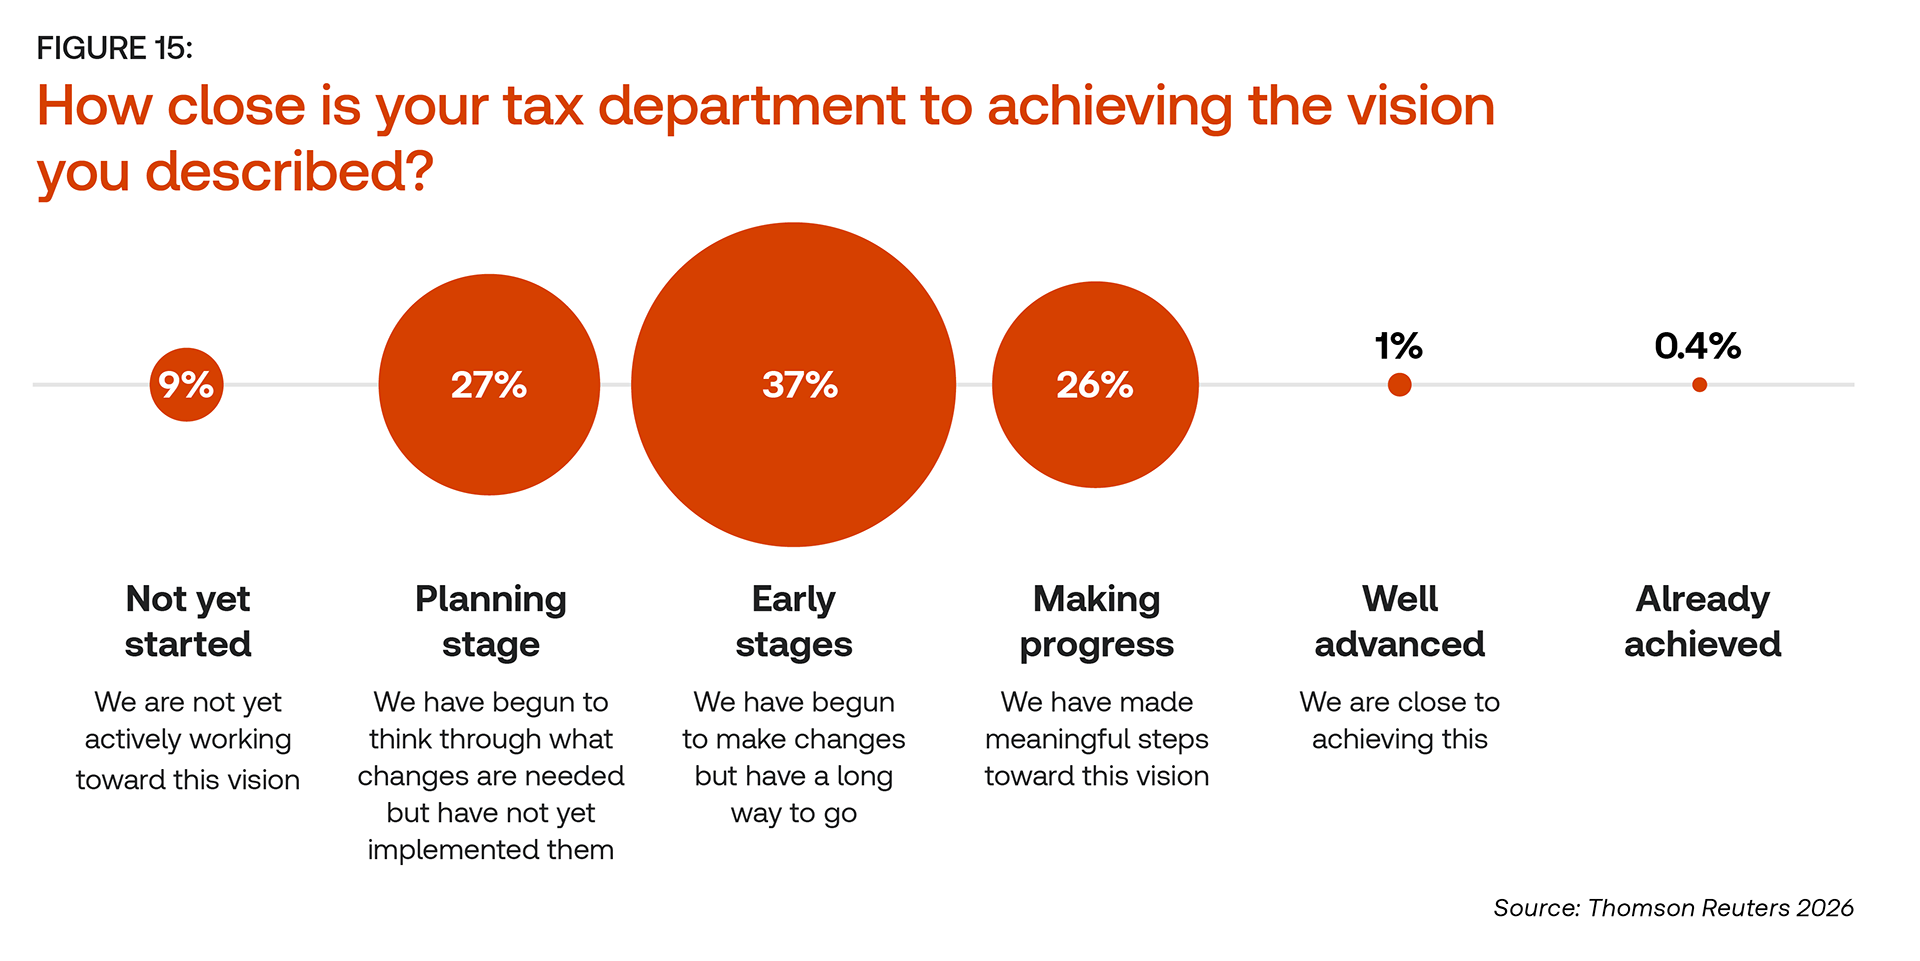
Taking an optimistic view, that means about two-thirds of respondents (64%) have at least moved beyond the planning stage. Of course, the determining factor will be how quickly they progress, because in a fast-moving, tech-driven environment, it will be essential to not fall behind.
How the tax leader role changes
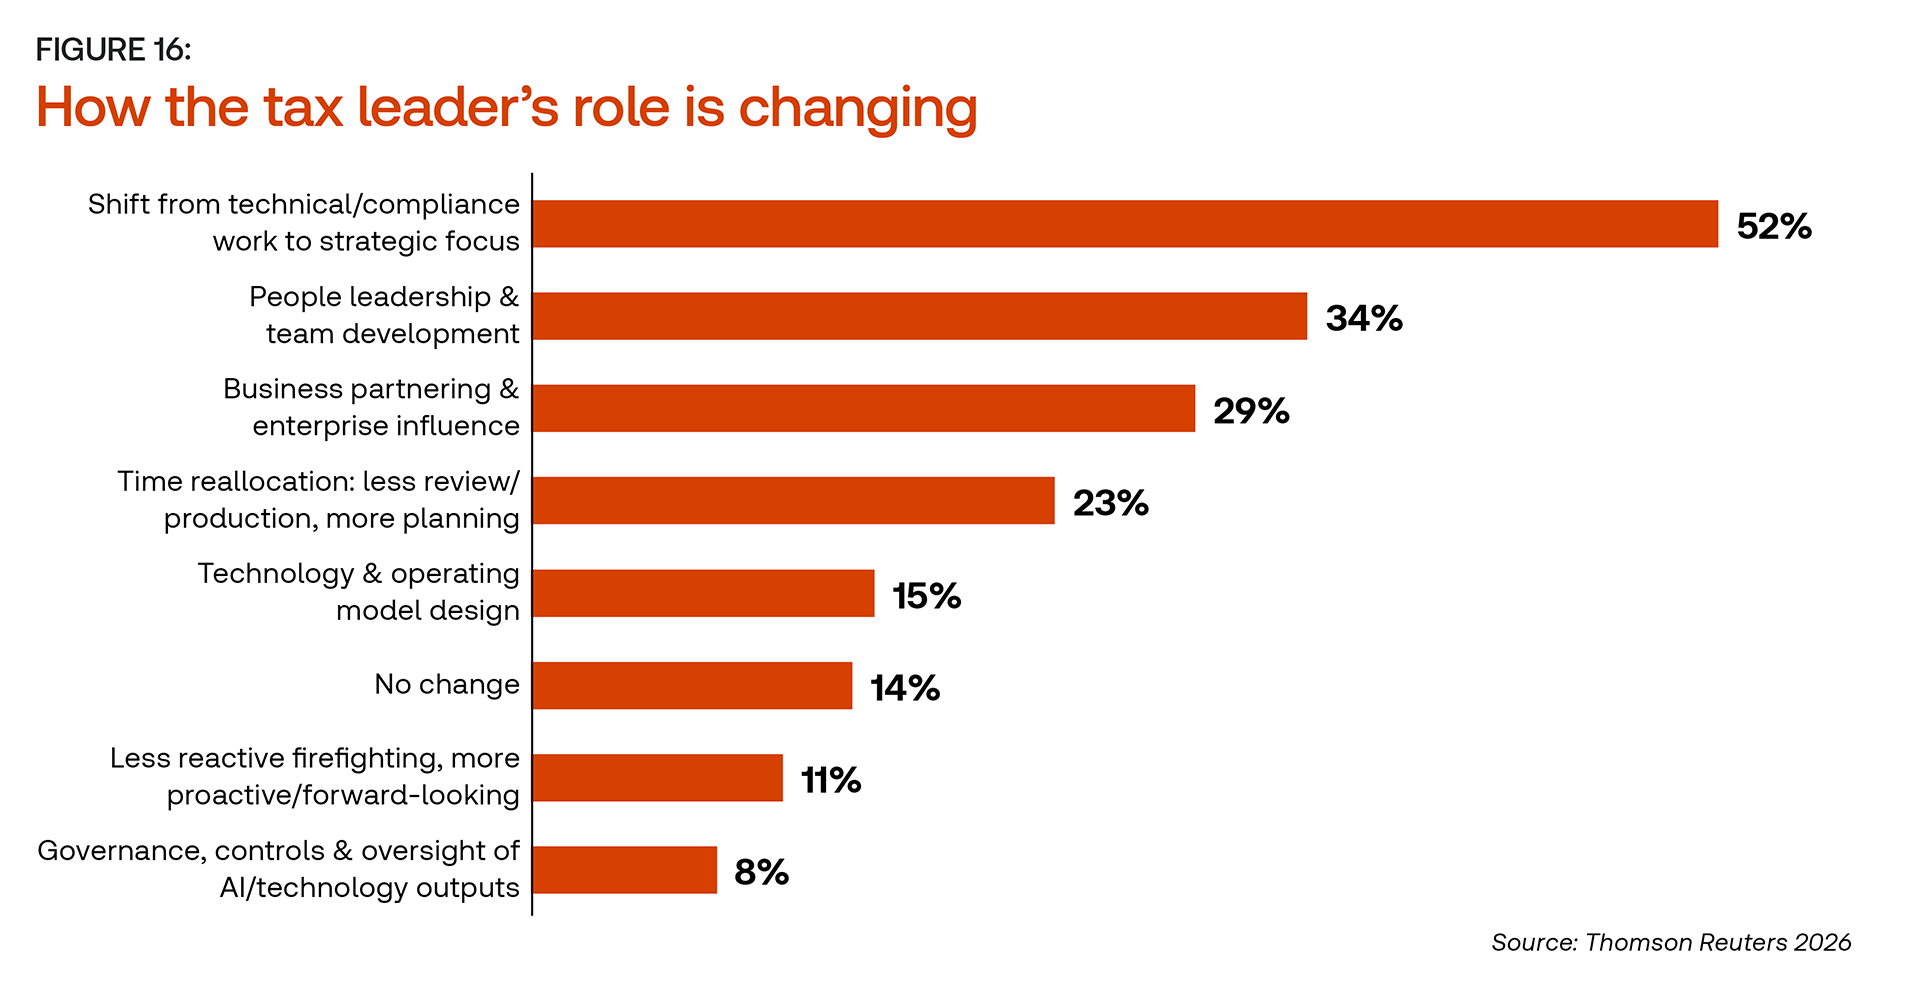
Much of the changes that will transform corporate tax functions over the next several years will, understandably, be driven from the top of the department. More than half of tax leaders say they expect their role to move to being more strategically focused and less concerned with overseeing basic tax work. They expect to spend more time planning, partnering with other parts of the business, and proactively strategizing and leading their teams, rather than reactively putting out fires.
In fact, one tax leader describes their role evolving to “spending less time on tax compliance matters and more time analyzing the tax function wholistically. I’ll spend more time as a standing voice on capital allocation, deal strategy, and regulatory risk.”
Another mentioned how they are shifting to a role with “less tax technical focus and more related to strategy and influence.”
Taking the necessary next steps
As this year’s State of the Corporate Tax Department report shows, tax functions stand at a critical moment. Transformation is underway, although slowly in many cases. However, for the first time in recent memory, corporate tax departments’ stated top priority is not a tax matter. Process automation and AI implementation now sit above compliance, tax planning, audit management, and legislative changes as key strategic priorities.
As their transformation journey continues, tax department leadership and professional teams are deciding what they want to be. Indeed, they can envision the 2030 version of their department in specific and consistent terms, and have identified the bottlenecks it needs to overcome in order to get there.
Indeed, these structural barriers — chiefly a lack or investment in the department — must be overcome in order to make the changes that tax leaders know that they need to make. The good news is that the planning has largely been done as close to two-thirds of tax leaders surveyed are already in the implementation stage on the path to their 2030 vision.
While time is still on the side of corporate tax departments, it may not be for long. And it will be up to tax department leaders to skillfully manage these necessary changes and adroitly lead their departments toward that vision.
Methodology
The Thomson Reuters Institute’s 2026 State of the Corporate Tax Department report is an in-depth analysis of survey responses from senior decision-makers in corporate tax departments around the world.
The findings were gathered through a 15-minute online global survey completed by 244 decision-makers in corporate tax departments. The surveys were conducted during July and August 2026.
A large percentage (92%) of survey respondents were in leadership positions, including chief tax officers, VPs of tax, senior directors, and managers. Respondents also included tax technologists. Additionally, 34 CFOs were surveyed for the report.
More than half of respondents were from companies based in the United States. Excluding their home country, 16% have tax obligations in between 4 and 15 other countries, 19% in 15 to 40 countries, and 13% in 40 or more. Notably, many respondents said that their global footprint was so wide that they could not readily provide how many jurisdictions in which their organization has tax obligations.
All figures in this report are drawn from the 2026 State of the Corporate Tax Department survey unless otherwise stated. Where year-over-year comparisons appear, they are drawn from the 2025 and 2024 iterations of the same study. Quotations are taken verbatim from open-ended survey responses and are reproduced without attribution.
Connect with the Thomson Reuters Institute
Topics
Have questions?

Featured Event
The 26th Annual Law Firm COO & CFO Forum